
Ghana’s ambition to introduce non-interest banking has encountered another hurdle after the Bank of Ghana (BoG) decided to delay the release of its regulatory framework to allow for broader consultations and address concerns surrounding the proposed financial model.
The framework, which was initially expected to be introduced before the end of December, will now take longer as the central bank seeks to build wider public understanding and acceptance before opening the door to a new category of financial service providers.
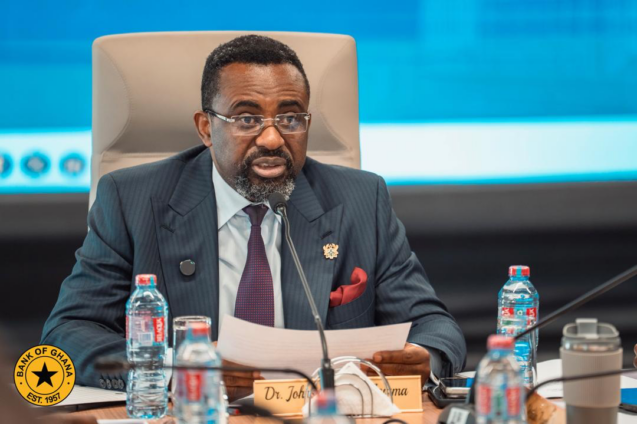
Governor of the Bank of Ghana, Dr Johnson Pandit Asiama, disclosed that although preparations were progressing, the central bank was unwilling to rush the process in the face of public unease.
His comments suggest that Ghana’s plans for non-interest banking are entering a critical consultation phase, with the regulator prioritising public confidence over an ambitious implementation timeline.
“Remember the last time there was some agitation from segments of society, so we needed to do some additional consultation.”
Dr Johnson Pandit Asiama
The decision reflects the sensitivity surrounding the proposed banking model and the importance of securing public confidence before introducing a framework that could reshape parts of Ghana’s financial services industry.
Public Concerns Force BoG to Reconsider December Timeline
The prospect of non-interest banking has generated considerable attention in Ghana, with discussions extending beyond financial regulation into questions about the nature, purpose and potential implications of the model.
Rather than proceeding with the December deadline, the Bank of Ghana appears determined to address lingering concerns and ensure that the framework is properly understood before implementation.
Dr Asiama indicated that the central bank was not treating the original timeline as an inflexible commitment.
“It doesn’t have to be necessarily before end of December,” he added. “We will make sure everyone is satisfied and convinced that this is something we have to do for the benefit of Ghanaians.”
The Governor’s remarks point to a deliberate change in approach. Instead of prioritising speed, the regulator wants to ensure that the proposed framework can operate within an environment of public understanding and institutional confidence.
This is particularly important given the potential for misunderstandings about non-interest banking, especially in a market where conventional interest-based banking remains the dominant financial services model.
Kenya and Malaysia Become Critical Reference Points
The Bank of Ghana is also drawing lessons from countries that have already established non-interest banking arrangements.
Dr Asiama revealed that a committee assigned to study the model internationally had visited Kenya and Malaysia and returned to Ghana the previous week.
The two countries were selected because of their experience with the framework and the lessons their financial systems could offer Ghana as it prepares its own regulatory arrangements.
The committee’s findings are expected to shape the next stage of the consultation process.
“Next week we are going to sit and digest the reports from those two countries,” he said. “It is a framework that is working and working well.”
Dr Johnson Pandit Asiama
Kenya’s experience is particularly relevant to Ghana’s ongoing preparations, with the Governor pointing to the country’s successful operation of the model over time.
Malaysia also offers an important reference point, given its established non-interest financial services industry and experience developing the regulatory structures needed to support it.
The central bank’s decision to study these jurisdictions suggests that Ghana wants to avoid unnecessary implementation challenges by learning from markets where the system is already operational.
However, the success of the model elsewhere does not automatically guarantee a smooth introduction in Ghana. Its eventual performance will depend on the strength of the regulatory framework, public understanding and the willingness of financial institutions to participate.
BoG Rejects Religious Controversy, Emphasises Business Opportunities
One of the central issues surrounding the proposed framework has been the need to clarify what non-interest banking represents within Ghana’s financial system.
Dr Asiama sought to position the initiative as a business and financial services development rather than an intervention designed to favour a particular religious group.
“It is just another player in the spectrum of financial service providers. We are looking at the business side of things.”
Dr Johnson Pandit Asiama
Under the model, financial institutions neither pay nor receive interest in the conventional sense. Instead, transactions are structured around arrangements that comply with non-interest banking principles.
The framework is intended to complement existing conventional banking services rather than replace them.
This distinction is important because the introduction of non-interest banking could expand the range of financial products available to individuals, businesses and institutions seeking alternatives to conventional interest-based arrangements.
It could also create additional opportunities for financial institutions to attract customers who have previously remained outside certain segments of the banking industry because of their financial or ethical preferences.
The challenge, however, will be ensuring that the framework is sufficiently clear to prevent misconceptions about its purpose and operation.
Three Licence Applications Already on the Table
Despite the delay in releasing the framework, interest in Ghana’s proposed non-interest banking market appears to be developing.
Earlier this month, Dr Asiama disclosed that the Bank of Ghana had already received three licence applications from institutions interested in operating under the proposed arrangement.
The applications indicate that prospective players are positioning themselves ahead of the formal introduction of the regulatory framework.
This development raises expectations about the potential scale of participation once the central bank completes its consultations and establishes the necessary licensing requirements.
However, receiving licence applications does not mean that the institutions have been approved to commence operations. The final regulatory requirements and approval processes will remain critical to determining how the market develops.
Ghana’s Banking Industry Awaits Regulatory Clarity
The latest delay places the spotlight on the Bank of Ghana’s ability to balance financial innovation with public confidence.
Non-interest banking could introduce additional competition, widen financial choices and create opportunities for previously underserved segments of the market.
Yet, the central bank must first establish a framework that is technically sound, commercially viable and sufficiently understood by the public.
The experience of Kenya and Malaysia may provide useful guidance, but Ghana’s regulatory approach must also reflect the country’s financial sector conditions and institutional realities.
With three licence applications already received and consultations still ongoing, the proposed framework remains an important development to watch.
The December deadline may no longer be decisive. What matters now is whether the Bank of Ghana can produce a framework that attracts credible operators, commands public confidence and strengthens the country’s financial services industry without creating unnecessary controversy.
Ghana’s non-interest banking ambitions remain alive, but the regulator has made it clear that implementation will not be rushed at the expense of wider acceptance.
READ ALSO: 2027 Budget: Manganese Processing Projected to Cost Gov’t One Gigawatt Power