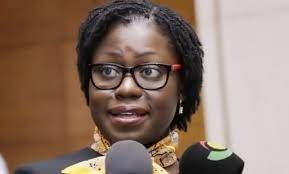
Mrs. Elsie Addo Awadzi, Second Deputy Governor of the Bank of Ghana has urged Rural and Community Banks (RCBs) to augment their capital base as needed in order to deploy more sophisticated systems and structures in line with the Bank of Ghana’s 2018 Cyber and Information Security Directive.
According to her, the directive provides for the adoption of minimum technical, governance, data protection protocols, and transaction monitoring and fraud detection and mitigation tools, to help mitigate key risks from digitization.
Speaking at the 21st annual national RCB CEOs conference, Mrs. Elsie Addo Awadzi noted that another key area the RCB sector needs to look closely at in its quest to reposition itself, is governance.
She underscored that several RCBs are yet to fully comply with the Bank of Ghana’s 2021 Corporate Governance Directive for Rural and Community Banks. The Directive seeks to promote higher standards of corporate governance and risk management to help strengthen the safety, soundness, and resilience of RCBs and ultimately the safety of their depositors’ funds and our financial system.
“Good corporate governance is a shared responsibility for all key stakeholders. Shareholders of RCBs are required to contribute adequate capital to fund their banks’ operations, and must appoint directors who meet the Bank of Ghana’s Fit and Proper test and can effectively steer the affairs of their banks.”
Mrs. Elsie Addo Awadzi
She further indicated that RCB Boards of Directors must take their oversight responsibilities under the law very seriously. She reminded the membership of the Board of an RCBs that it “is not for personal prestige” because it carries a significant burden of personal and collective responsibilities and liabilities. She urged Board members to put in place strategic plans that are well executed by management with appropriate risk management, transparency, and accountability.
“The Bank of Ghana finds it worrying that it continues to receive many petitions from whistle-blowers alleging serious acts of impropriety involving directors and senior management of RCBs. We expect that these would be a thing of the past as RCB fully comply with the Corporate Governance Directive.”
Mrs. Elsie Addo Awadzi
Staff to ensure high levels of utmost good faith in the discharge of their duties
Speaking on the role of RCB Staffs, she emphasized that members are expected to ensure high levels of utmost good faith in the discharge of their duties.
Making reference to Bank of Ghana’s 2021 Fraud Report for the banking sector, Mrs. Elsie Addo Awadzi highlighted that the RCB sector recorded the highest level of employee involvement (46.04%) in fraud cases, due to poor internal controls among other things.
She disclosed that staff found culpable were blacklisted by the Bank of Ghana from working in the banking Industry.
“We expect that RCBs will continue to strengthen their internal controls and promote high standards of legal and ethical behavior by staff.”
Mrs. Elsie Addo Awadzi
Still speaking on ways to reposition the RCB sector, Mrs. Elsie Addo Awadzi noted that RCBs should adopt sustainable banking practices contained in Ghana’s Sustainable Banking Principles launched by the Bank of Ghana in November 2019. Universal banks, she said, are already implementing these principles that require them to manage Environmental, Social, and Governance (ESG) risks in their operations.
Charge to promote cleaner and more environmentally sustainable ways of doing business
The Second Deputy Governor of the BoG further underscored that RCBs must use their lending power to promote cleaner and more environmentally sustainable ways of doing business in their various communities, and promote social inclusion through lending to women, youth, and other marginalized groups, so that no one is left behind.
She added that RCBs must also reflect ESG principles in their internal policies to reduce their own carbon footprint, and to promote more gender diversity in their leadership. She expressed her dissatisfaction when she heard from the Chairperson for the occasion that there are currently only 10 female CEOs among the 147 CEOs representing the sector.
“Where are all the women? Gender equity in leadership will have immense benefits for the sector and for your customers. It is not only a good thing to do; it is also good for business, and so this is clearly one area in which we need to see some change.”
Mrs. Elsie Addo Awadzi
To reposition the RCB sector, it is important to take stock of its performance over the last almost five decades of its existence, to assess what has worked and what has not worked well.
The sector has several strengths such as the strong participation of communities and local stakeholders in the ownership and governance of RCBs which provides strong local support and goodwill for their businesses. Some of these RCBs have operated in their communities for decades and have become key players in shaping the destinies of these communities, providing a source of financing for generations of families of businesses.
READ ALSO: Cyber Security Is a Personal Decision – Maximus Ametorgoh