
The Bank of Ghana (BoG) is preparing to tighten its oversight of digital financial services as artificial intelligence (AI) and emerging technologies reshape banking operations, cybersecurity and risk management across the financial sector.
The move signals a new phase in the central bank’s efforts to ensure that technological innovation does not expose financial institutions, businesses and customers to emerging threats.
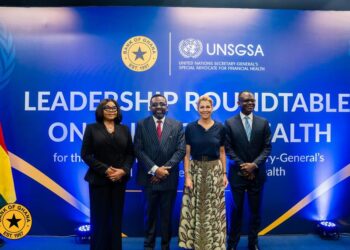
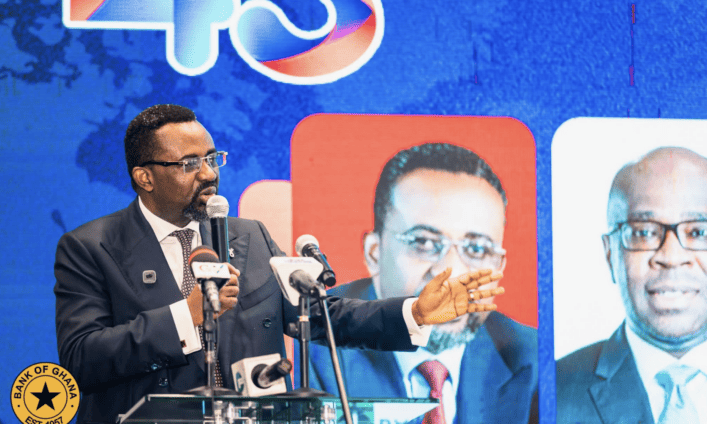
Dr Johnson Pandit Asiama, Governor of the Bank of Ghana, has disclosed that the central bank is developing a directive to regulate the use of artificial intelligence in the financial sector, with a focus on encouraging innovation while addressing the risks associated with the rapidly evolving technology.
The proposed directive comes at a time when financial institutions are increasingly exploring digital solutions to improve service delivery, strengthen fraud detection, assess creditworthiness and reduce operational costs.
However, the growing reliance on technology is also creating new challenges for regulators, particularly in areas involving cybersecurity, data protection, operational resilience and consumer safety.
The BoG’s latest initiative suggests that financial institutions may need to pay closer attention to how AI systems are developed, deployed and monitored as digitalisation continues to transform the industry.
BoG Moves to Establish Rules for Artificial Intelligence
Artificial intelligence is becoming an increasingly important tool in modern banking, offering financial institutions opportunities to automate routine processes, analyse large volumes of customer data and identify suspicious transactions more quickly.
The technology can also support credit assessment by helping banks evaluate borrowers and make lending decisions using information that may be difficult to process through traditional methods alone.
Recognising these benefits, Dr Asiama said the central bank was not seeking to discourage technological advancement but wanted to ensure that innovation occurred within an appropriate regulatory framework.
“Our approach will seek to promote responsible experimentation and innovation while ensuring appropriate governance throughout the AI lifecycle.”
Dr Johnson Asiama
The proposed directive is expected to form part of the BoG’s broader efforts to strengthen financial sector regulation as digital technologies become more deeply embedded in banking operations.
The emphasis on governance throughout the AI lifecycle is particularly significant because risks can emerge at different stages, including data collection, model development, deployment and ongoing monitoring.
Poor-quality data, flawed algorithms and inadequate oversight can undermine the reliability of AI-driven decisions. In financial services, such weaknesses could affect lending outcomes, fraud detection and the treatment of customers.
Establishing appropriate safeguards will therefore be important in ensuring that financial institutions can benefit from AI without compromising accountability and public confidence.
Cybersecurity Threats Put Banks Under Pressure
While AI presents opportunities for efficiency and innovation, the BoG is also paying increasing attention to the security challenges accompanying the digital transformation of financial services.
Dr Asiama identified cybersecurity, digital fraud, data protection, third-party dependencies and cloud computing among the areas receiving increasing supervisory attention.
These risks have become increasingly relevant as banks expand their digital platforms and depend more heavily on interconnected systems to deliver services.
A cybersecurity breach can disrupt banking operations, expose confidential customer information and undermine confidence in financial institutions. Digital fraud can also result in financial losses for customers and banks, particularly when criminals exploit weaknesses in online platforms.
Meanwhile, greater dependence on external technology providers creates additional risks when financial institutions rely on third parties for data storage, software and critical operational services.
Cloud computing can improve flexibility and reduce the cost of managing technology infrastructure, but financial institutions must ensure that their arrangements provide adequate protection for sensitive information and essential services.
The BoG’s growing supervisory attention to these issues reflects the need for banks to strengthen their defences as financial transactions increasingly move through digital channels.
Revised Cybersecurity Directive Faces Closer Scrutiny
Beyond developing rules for artificial intelligence, the central bank is continuing efforts to strengthen existing cybersecurity requirements across the financial industry.
Dr Asiama said the BoG was working with the Ghana Association of Banks and other industry players to facilitate the implementation of its revised Cyber and Information Security Directive.
The collaboration is intended to support financial institutions as they work towards meeting the updated requirements and improving their ability to manage technology-related threats.
The central bank also intends to undertake thematic reviews focusing on the implementation of the revised directive.
Such reviews could help supervisors assess how effectively financial institutions are applying the requirements and identify areas where additional improvements may be necessary.
The approach places greater emphasis on implementation rather than simply requiring banks to establish cybersecurity policies on paper.
Financial institutions must demonstrate that their security arrangements are effective, regularly assessed and capable of responding to emerging threats.
The planned reviews also reinforce the importance of consistent risk management across the sector, particularly as institutions adopt new technologies and become increasingly interconnected.
Bank Executives Warned Against Treating Cybersecurity as an IT Issue
Dr Asiama has urged bank boards and senior management to treat cybersecurity and operational resilience as core business risks rather than merely technology issues.
The call highlights the responsibility of senior executives and directors in protecting financial institutions from disruptions that could threaten their operations, customers and financial stability.
Cybersecurity decisions can have consequences far beyond a bank’s technology department. A major security incident, for instance, could interrupt payments, compromise customer accounts and damage an institution’s reputation.
Operational resilience is equally important because financial institutions must be able to maintain essential services or restore them quickly when disruptions occur.
This requires management to ensure that cybersecurity, business continuity and risk controls are integrated into wider corporate decision-making.
Banks must also recognise that technological investments need to be supported by skilled personnel, appropriate internal controls and a culture that encourages employees to identify and report potential threats.
As AI adoption expands, these responsibilities could become even more demanding because institutions will need to monitor both conventional cybersecurity threats and risks associated with automated decision-making systems.
Ghana’s Financial Sector Faces a Critical Technology Shift
The BoG’s regulatory push comes as digitalisation continues to improve the speed, convenience and accessibility of financial services.
Digital platforms have created opportunities for banks to serve customers more efficiently, while technological advances have the potential to strengthen financial inclusion and improve the delivery of banking products.
However, these benefits depend partly on the ability of financial institutions to manage the risks that accompany innovation.
Dr Asiama said regulatory and supervisory frameworks must continue to evolve in response to technological change and increasingly interconnected financial risks.
He also called on banks to build strong risk-management cultures and sustainable business models to ensure that innovation supported the development of a resilient financial sector.
The proposed AI directive, combined with closer scrutiny of cybersecurity requirements, could therefore influence how financial institutions approach technology investments and risk governance.
Banks that embrace innovation will need to demonstrate that their systems are reliable, their customer information is protected and their decision-making processes are subject to appropriate oversight.
Ultimately, the challenge facing Ghana’s financial sector is to capture the benefits of artificial intelligence and digital banking without allowing technological vulnerabilities to weaken confidence in the system.
As the BoG develops its regulatory approach, financial institutions will need to prepare for a future in which innovation and stronger risk controls become increasingly inseparable.
READ ALSO: Ato Forson Vows New Economy Will End Ghana’s Unemployment Struggles