The way money moves across borders is entering a period of rapid transformation, with Artificial Intelligence (AI), stablecoins and other digital assets challenging the traditional systems that have long powered international commerce.
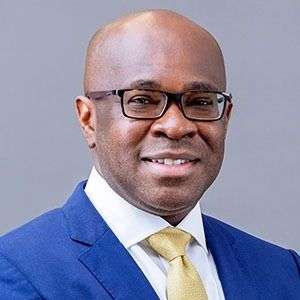
Chief Executive of Stanbic Bank Ghana, Kwamina Asomaning, has urged businesses to pay close attention to these developments and adopt financial technologies that can make cross-border transactions faster, safer and more efficient.
His comments come as businesses increasingly look beyond conventional payment channels in search of solutions that can reduce delays, improve transparency and make international transactions easier to manage.
AI Moves Into the Heart of Financial Services
AI is no longer simply a futuristic concept within banking. It is already being applied to several areas of financial services, changing how institutions identify risks, process information and support business decisions.
According to Mr Asomaning, AI is transforming key functions including fraud detection, regulatory compliance, reconciliation, liquidity management and foreign exchange decision-making.
These applications could have significant implications for companies engaged in international trade. Faster fraud detection can help reduce financial losses, while improved reconciliation can make it easier for businesses to track payments and match transactions.
AI-powered liquidity management could also help companies make better decisions about when and where funds should be deployed, particularly when they operate across several markets and currencies.
Foreign exchange decision-making is another area where technology could make a difference. Businesses dealing with multiple currencies constantly face the challenge of managing exchange rate movements and determining the most efficient way to settle international obligations.
The growing use of AI could provide businesses with more sophisticated tools to assess these transactions and make decisions based on large volumes of financial data.
Stablecoins Challenge Traditional Payment Models
While AI is transforming how financial institutions manage payments, digital assets are challenging the traditional mechanisms through which money moves across borders.
Mr Asomaning noted that innovations such as stablecoins, tokenised deposits and other digital assets are challenging traditional approaches to how quickly and efficiently money can move across borders.
Stablecoins have attracted attention because they are designed to maintain a relatively stable value while using digital infrastructure that can facilitate transfers. Tokenised deposits similarly explore how traditional bank deposits can operate within emerging digital financial systems.
These developments are prompting fresh questions about the future of international payments.
Businesses that once relied heavily on established banking corridors may increasingly have access to different routes for moving funds. The result could be a payments environment where companies have to assess several options before deciding how a particular transaction should be completed.
Businesses Must Choose Payment Routes Carefully
Mr Asomaning said the future of international payments may not be defined by a single payment system, currency or transaction corridor.
That shift could place greater responsibility on businesses to understand the available payment options and determine which route best suits each transaction.
Companies involved in imports, exports, regional trade and international investment could face an increasingly complex payments environment. The challenge will not simply be about adopting the newest technology. Businesses will also need to consider cost, speed, security, compliance and reliability.
The ability to make those decisions effectively could become an important part of managing international commerce.
Mr Asomaning cautioned against treating technology adoption as an objective in itself, stressing that innovation should ultimately solve practical problems for businesses.
“The question for us is not technology for technology’s sake. It is how these innovations can be harnessed responsibly to make international commerce simpler, safer, and more efficient for businesses. This is where Stanbic Bank brings a distinctive perspective.”
Kwamina Asomaning
Responsible Innovation Takes Centre Stage
The rapid development of digital financial technologies also brings new responsibilities for financial institutions and businesses.
Technology can create opportunities to improve payment efficiency, but its effectiveness depends on how responsibly it is deployed. Issues surrounding fraud, compliance, security and financial integrity remain important considerations as new payment models gain traction.
That makes the balance between innovation and responsible adoption increasingly important.
Businesses may therefore need to move beyond simply asking whether a new payment technology is available. The more important question could be whether the technology is appropriate for a particular transaction and whether it delivers measurable improvements without creating unnecessary risks.
Stanbic Eyes Integrated Payment Ecosystem
Stanbic Bank Ghana is also positioning itself around the changing payments environment.
Mr Asomaning said the bank is working to build an integrated payments ecosystem that will enable customers to transact across African, regional and global markets through a single banking relationship.
Such an approach could simplify international transactions for businesses operating across multiple jurisdictions.
Rather than managing fragmented relationships for different markets, companies could have access to a more connected banking structure capable of supporting transactions across several corridors.
The development also reflects the broader push toward greater financial integration across African markets, where businesses increasingly need payment solutions capable of supporting regional trade.
The Next Chapter of Global Payments
The combination of AI, stablecoins, tokenised deposits and other digital assets is creating a new chapter for cross-border payments.
Traditional payment systems are unlikely to disappear overnight, but the emergence of alternative technologies is changing expectations around speed, efficiency and accessibility.
Businesses that understand these developments will be better placed to assess the payment routes available to them as international commerce becomes increasingly digital.
Innovation matters, but its value will ultimately depend on whether it makes commerce simpler, safer and more efficient.
As digital finance continues to evolve, the competition may increasingly centre not only on who can move money, but on who can move it intelligently, responsibly and efficiently across borders.