Ghana’s banking sector has slipped deeper into foreign hands, and the numbers paint a stark picture that leaves little room for comfort.
Foreign-owned banks now control more than 60 percent of the industry’s total assets, a dominance that has quietly expanded over the past decade and shows no sign of easing. With industry assets sitting at GH¢500.2 billion as of August 2026, that means foreign institutions hold more than GH¢300 billion of the country’s banking wealth. Locally owned banks, both private and state-controlled, are left sharing less than GH¢200 billion between them.
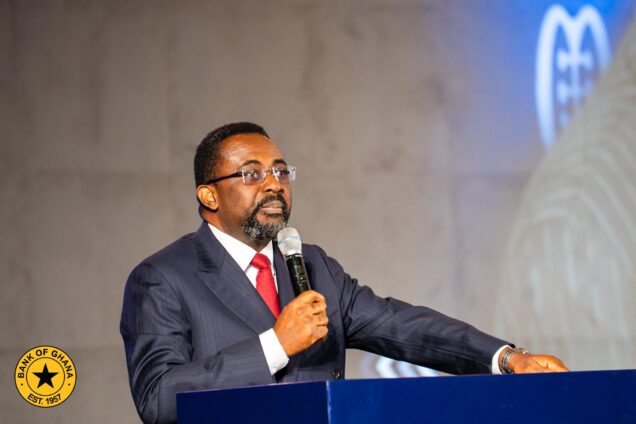
Bank of Ghana Governor Dr Johnson Pandit Asiama did not mince words when he addressed the issue after the 133rd Monetary Policy Committee meeting. “The current regime where over 60 percent of total banking assets accrue to foreign-owned banks, from a strategic point of view, that may not be very, very optimal. And so going forward, we will want to see our local banks increase their participation in the sector,” he said.
A Dramatic Shift Since the Clean-Up Years
The imbalance did not appear overnight. In 2017, Ghanaian-owned banks still held close to half of the industry’s assets. State-owned banks controlled 16.6 percent while domestically controlled private banks held 32.3 percent.
Foreign banks took the rest. That balance tilted sharply during the 2017 to 2019 banking sector clean-up. The exercise wiped out nine universal banks, every one of them indigenous: UT Bank, Capital Bank, UniBank, The Royal Bank, Beige Bank, Sovereign Bank, Construction Bank, Premium Bank and Heritage Bank.
UT Bank and Capital Bank collapsed first in August 2017, their deposits and selected assets transferred to GCB Bank. A year later, five more local banks were folded into the newly created Consolidated Bank Ghana.
The government issued a GH¢5.76 billion bond just to retire the debt of those five institutions. At the same time, the minimum capital requirement jumped from GH¢120 million to GH¢400 million by December 2018. A group of indigenous banks asked for a longer phased timeline, but the deadline stayed firm. Foreign banks, better capitalized and backed by parent groups, weathered the storm with relative ease.
Foreign Giants Dominate the Top Tier
The results of that upheaval remain visible today. According to PwC Ghana’s 2026 Banking Survey, four of the six largest banks by operating assets in 2025 were foreign-owned subsidiaries. Ecobank held 10.8 percent of industry operating assets, Stanbic 8.6 percent, Absa 7.2 percent and Zenith 6.1 percent.
State-controlled GCB Bank still sits at the top with 12.3 percent of operating assets, 12.37 percent of deposits and 17.8 percent of loans and advances. Yet the concentration of foreign power is unmistakable.
Profits tell a similar story. Of the five banks that posted the highest profit before tax in 2025, four were foreign-owned. GCB led with GH¢3.16 billion, followed by Ecobank with GH¢2.98 billion, Absa with GH¢2.74 billion, Stanbic with GH¢2.61 billion and Guaranty Trust Bank with GH¢1.56 billion. Nigerian banks alone form a powerful bloc. The Ghanaian subsidiaries of First Bank, UBA, Guaranty Trust Bank, Access Bank and Zenith Bank recorded a combined pre-tax profit of GH¢1.20 billion in the first quarter of 2026 alone.
Secured Lending Still Heavily Tilted
The grip extends deep into credit markets. In the second quarter of 2026, foreign-owned banks registered GH¢14.12 billion in secured credit, accounting for 71.1 percent of the GH¢19.9 billion recorded by the banking sector.
Ghanaian-owned banks managed GH¢5.74 billion. Their share remains smaller, but their growth rate is eye-catching. Secured lending by local banks surged 112.4 percent from the GH¢2.70 billion they registered a year earlier. Foreign banks grew at a more modest 19.3 percent over the same period.
Governor Asiama has made his preference plain. “If at all, what we want to see is a greater amount of those assets should be held by our local banks. For me, if there’s anything I want to see with that trend, it will be to see more of our local banks holding those assets as we go forward,” he said. He added, “We need to do some work to ensure that our local banks, our indigenous banks, are able to thrive and are able to compete.”
What the Concentration Means on the Ground
The concentration carries real consequences. Profits and dividends earned by foreign subsidiaries often leave the country, adding pressure on foreign exchange.
Credit decisions at those banks are frequently shaped by group-level risk appetites set outside Ghana. Local businesses, particularly smaller ones, can find themselves navigating lending standards designed in distant boardrooms rather than tailored to the Ghanaian context.
Nigeria offers a contrasting example. There, central bank policies helped local banks build scale until privately owned Nigerian banks held 94 percent of banking assets. Ghana has moved in the opposite direction. The clean-up years removed weak local players but also left a vacuum that foreign institutions filled quickly and thoroughly.
Local banks are not standing still. Their faster growth in secured lending shows they are expanding credit books at a rapid clip. GCB continues to lead in several key metrics. Mid-tier indigenous players have also recorded gains in deposits and market share. Still, the overall asset base remains heavily tilted toward foreign ownership.
The Bank of Ghana has signaled it intends to push for greater local participation. Strengthening risk management frameworks, improving governance at indigenous banks and creating conditions that allow them to scale remain priorities. Whether those efforts can reverse a decade-long shift remains the central question hanging over Ghana’s financial system. The foreign banks arrived with capital, expertise and global networks. They have used those advantages to tighten their hold. Local institutions now face the challenge of closing a gap that has only grown wider with time.