Africa’s nuclear energy ambitions are entering a more consequential phase as a growing number of countries move from political declarations towards the institutional, technical and financial work required to build their first reactors.
A new assessment of the global nuclear industry identifies Ghana, Kenya, Nigeria and Uganda as African countries pursuing nuclear power programmes, while Egypt is already constructing its first nuclear plant.
The development places Ghana within a broader continental race to secure dependable, lower-carbon baseload electricity, but it also exposes the difficult gap between announcing nuclear ambitions and creating the conditions required to deliver them.
For Ghana, that distinction is particularly important. The country has already established the principal institutions for a nuclear programme and officially moved into Phase Two of the International Atomic Energy Agency’s milestone framework.
Yet its programme still faces questions around financing, site studies, regulation, grid readiness, human capacity and the eventual economics of the plant.
The global picture offers both encouragement and caution. Nuclear generation reached a record 2,703 terawatt-hours in 2025, but nuclear’s share of global electricity generation fell to 8.8%, while operating capacity declined slightly.
China accounted for the entire increase in global nuclear generation during the year, illustrating how concentrated the sector’s recent expansion has become.
Africa’s Nuclear Ambition Meets A Difficult Global Reality
The case for nuclear power in Africa is being driven by a straightforward problem: electricity demand is rising while governments are under pressure to expand reliable generation without locking their economies into increasingly costly or carbon-intensive energy systems.
But the global nuclear experience suggests that nuclear power is not a quick solution to an electricity deficit.
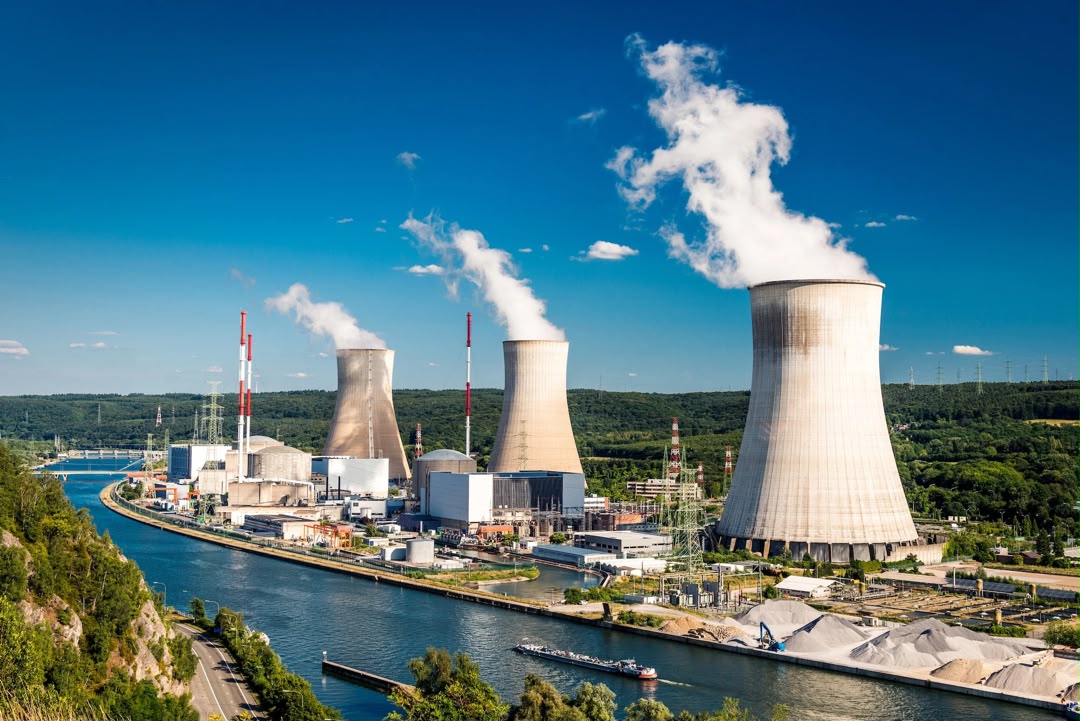
By mid-2026, 73 reactors were under construction across 14 countries, with China accounting for 37 of them. Yet between 25 and 28 of those projects were reportedly behind schedule, while none of the 16 reactors connected to grids between 2023 and 2025 was completed on time.
That record matters for Ghana because a nuclear programme involves commitments extending far beyond the construction of a generating plant.
Financing structures, regulatory institutions, nuclear safety, radioactive waste management, emergency preparedness, fuel arrangements, skilled personnel and grid infrastructure all have to mature alongside the project.
Ghana has therefore reached a point where the quality of implementation may matter more than the ambition of its nuclear target.
The Nuclear Regulatory Authority says Ghana’s programme is being coordinated through the Ghana Nuclear Power Programme Organisation, bringing together government institutions, private companies, academia and the three key nuclear institutions: the Nuclear Regulatory Authority, Nuclear Power Ghana and the Nuclear Power Institute.
That institutional architecture is significant because nuclear power cannot be treated simply as another generation project. It requires a permanent regulatory and technical ecosystem capable of sustaining the industry throughout the plant’s operating life and eventual decommissioning.
Ghana’s Power System Determines The Scale Of The Opportunity
For Ghana, the immediate attraction of nuclear power lies in its potential contribution to a more diversified electricity mix.
The country is already heavily dependent on thermal generation alongside hydropower, while electricity demand has expanded significantly as economic activity, urbanisation and industrial consumption have increased.
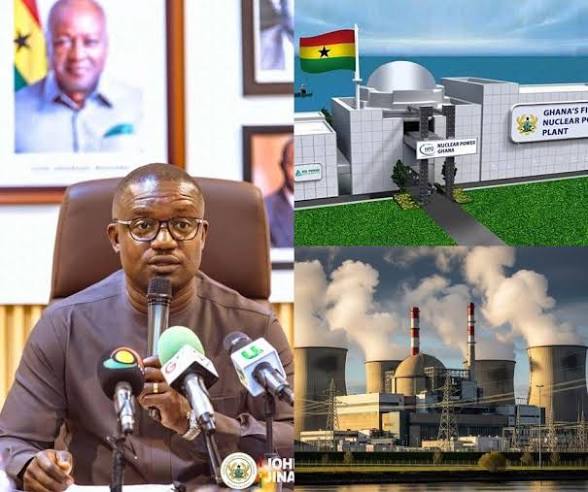
Energy Minister John Jinapor has described nuclear power as a critical component of Ghana’s future energy mix, particularly as the country seeks reliable electricity for industrialisation.
Government figures cited in August showed peak electricity demand had risen to about 4,500MW, compared with roughly 300MW when the Akosombo Dam was commissioned.
That trajectory strengthens the argument for adding a source capable of providing continuous generation.
But the scale of Ghana’s existing grid also imposes a constraint.
The global nuclear assessment estimates Ghana’s installed generating capacity at approximately 5GW and notes that integrating a large conventional reactor could require significant investment in transmission and system stability.
This is where the choice of nuclear technology becomes strategically important.
Ghana has been examining small modular reactor options as part of its preparations, while a nuclear power plant simulator acquired for training purposes is already being used to build operational and safety competencies. The simulator features a NuScale design, with the configuration demonstrated at the centre upgraded to 77MW per module.
The relevance is not simply technological.
A modular approach could potentially allow Ghana to align nuclear additions more closely with the capacity and stability of its electricity system rather than attempting to introduce a very large block of generation at once.
But technology cannot compensate for weak project fundamentals.
Financing May Become Ghana’s Defining Test
Perhaps the most immediate challenge is money.
Nuclear projects require substantial upfront capital, long development periods and financing arrangements that can remain viable over decades.
For a country managing competing infrastructure needs and fiscal pressures, the financing model could ultimately determine whether Ghana’s nuclear ambitions move from preparation to construction.
This issue has already surfaced in Ghana’s programme.
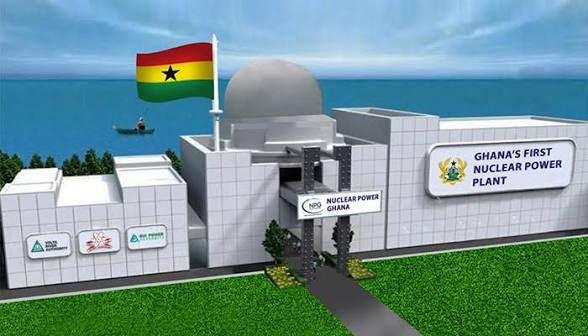
Earlier in 2026, Nuclear Power Ghana warned that critical technical studies, including detailed site characterisation and environmental impact assessment, were facing funding constraints.
The organisation said these studies were necessary for completing the feasibility assessment and advancing towards construction readiness.
That creates a revealing paradox.
Ghana is trying to develop one of the most technically demanding infrastructure projects in its energy history, yet some of the preparatory work required to make that project bankable has itself faced funding challenges.
The lesson from the continent is that political commitment is only the beginning.
Kenya, for example, has announced plans to begin construction of a large reactor in March 2027, but the global assessment questioned the credibility of that timetable because important details concerning technology, financing and construction arrangements remained unclear.
Uganda has similarly announced ambitious nuclear capacity plans without, according to the assessment, having confirmed a technology provider, financing model or complete legislative framework.
Ghana therefore has an opportunity to distinguish itself by ensuring that each stage of its programme is backed by demonstrable technical and financial readiness.
Egypt Offers Ghana A Different African Reference Point
Egypt provides perhaps the most relevant continental comparison.
Unlike Ghana, Egypt has moved into actual reactor construction, with four Russian-designed VVER-1200 units being built at El Dabaa.
However, even that project has encountered delays, with the first unit’s commissioning pushed from an earlier 2026 expectation to 2028. Egypt is also expected to begin repaying a US$25 billion Russian loan from 2029.
The Egyptian experience illustrates both the transformative potential and the financial weight of nuclear development.
For Ghana, the lesson should not simply be that nuclear power is achievable in Africa. It should be that the financing, contracting and repayment implications must be understood before construction begins.
A nuclear plant that provides reliable electricity but creates unsustainable fiscal obligations would not necessarily strengthen Ghana’s energy security.
The objective must therefore be to secure electricity that is not only dependable and low-carbon, but economically sustainable.
Human Capacity Is As Important As The Reactor
The other major issue is Ghana’s ability to build and retain the skills needed to operate a nuclear industry.
Government has acknowledged that technical capacity must be developed alongside physical infrastructure.
At the US-Africa Nuclear Energy Summit in Accra, Emmanuel Armah-Kofi Buah, then representing the government, put the issue bluntly:
“Human capacity in itself is infrastructure. We, therefore, cannot build physical infrastructure today and hope to find the people tomorrow. We must build both.”
That principle could become one of the most important tests of Ghana’s programme.
A nuclear plant creates demand for nuclear engineers, reactor operators, radiation specialists, safety professionals, regulators, technicians, emergency-response personnel and other highly specialised workers.
The simulator now available at the Ghana Atomic Energy Commission is therefore more than a training facility. It represents an attempt to build institutional memory before Ghana has an operating reactor.
For Ghana, the longer-term opportunity is even broader: nuclear development could support engineering services, research, specialised manufacturing, maintenance and professional services if local participation is deliberately built into the programme.
Nuclear Must Fit Into A Wider Ghanaian Energy Strategy
The central question for Ghana is therefore not whether nuclear power can generate electricity.
It can.
The more important question is whether Ghana can develop nuclear generation without weakening the rest of its energy system or creating a financial burden that undermines the very industrial transformation the programme is intended to support.
Nuclear should consequently be considered alongside natural gas, hydropower and renewable energy rather than as a replacement for them.
The global evidence reinforces that approach. While nuclear production reached a record in 2025, solar and wind capacity expanded by 510GW and 159GW respectively. Globally, wind and solar are continuing to expand at a pace that nuclear has struggled to match outside China.

For Ghana, that means the nuclear programme should strengthen diversification rather than become another form of energy dependence.
The country has already identified nuclear as part of its long-term generation strategy. Its 2026–2029 development plan includes the diversification of baseload electricity through clean nuclear technology, alongside cooperation with the IAEA, capacity building and engagement with international partners.
The strategic opportunity is therefore clear: use nuclear power to strengthen the reliability of the electricity system while continuing to expand renewable generation and improve the efficiency of existing resources.
Ghana’s Nuclear Test Is Now About Execution
Africa’s nuclear expansion is still at an early stage, but the direction of travel is becoming clearer.
South Africa remains the continent’s only operating nuclear power producer, while Egypt is building its first plant and Ghana, Kenya, Nigeria and Uganda are developing programmes at different stages.
For Ghana, this creates both competition and an opportunity to learn from the countries moving ahead.
Its advantage is that it does not have to repeat every mistake made elsewhere.
Ghana can build financing discipline into its programme, strengthen its regulatory framework before construction, develop the workforce ahead of commissioning, ensure the grid can absorb the capacity and establish transparent arrangements around costs and long-term liabilities.
The country has already moved beyond the stage of merely discussing nuclear power. The regulator confirms that Ghana is in Phase Two of the IAEA framework, while recent government statements point to progress in site studies, regulatory preparation and capacity development.
The next stage will determine whether that institutional progress can be converted into a financeable and construction-ready project.
For Ghana, nuclear power is therefore no longer simply an energy aspiration. It is becoming a test of whether the country can turn a long-term infrastructure vision into a disciplined, technically credible and economically sustainable national project.
READ ALSO: Ghana’s Benchmark Lending Rate Falls Further to 10.04%