Tullow Oil Plc has expressed disappointment after an International Chamber of Commerce (ICC) tribunal ruled that a US$196.5 million corporate income tax assessment arising from business interruption insurance proceeds did not breach its petroleum agreements with Ghana.
The company has not announced an appeal or specified any further legal action. Instead, Tullow said it would consider its next steps following further engagement with the Government of Ghana, leaving the immediate focus on how the award will be implemented and how the parties manage their wider relationship.
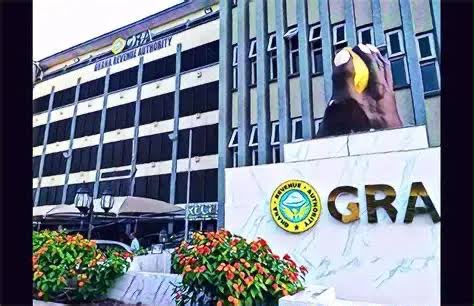
The dispute centres on insurance proceeds received by Tullow during the 2016–2019 financial years. The Ghana Revenue Authority (GRA) subsequently issued a corporate income tax assessment of US$196.5 million in relation to those proceeds.
Tullow challenged the assessment through international arbitration, arguing that it was inconsistent with the contractual protections contained in its Petroleum Agreements with Ghana. The ICC tribunal has now rejected that central argument.
“Tullow is disappointed that the Tribunal has come to this decision and will now consider next steps after further engagement with the Government of Ghana.”
Tullow Oil Plc
The company said it would provide an update in due course, but its statement did not identify what those next steps might entail. That distinction is important: Tullow has expressed dissatisfaction with the outcome, but has not stated that it will pursue another legal challenge.
The Dispute And What The Tribunal Decided
At the centre of the arbitration was the question of whether Ghana’s tax assessment was compatible with the contractual protections governing Tullow’s petroleum operations in the country.
The tribunal ruled that the US$196.5 million assessment did not breach those agreements. It also determined that the 100% penalties attached to the assessment fell outside the contractual protections contained in the Petroleum Agreements.
Tullow’s original arbitration request formed part of a wider dispute with Ghana over tax assessments. The company had referred two separate assessments to the ICC in 2023, including the US$196.5 million assessment relating to business interruption insurance proceeds and a separate assessment concerning the disallowance of loan interest.
The latest award relates to the insurance proceeds dispute.
The financial significance of the case, however, extends beyond the original US$196.5 million figure. Ghana’s government has presented the tribunal’s decision as upholding a broader tax assessment of US$393.09 million, comprising the tax assessment and the associated 100% penalty.
That broader figure was highlighted by Finance Minister Dr Cassiel Ato Forson following the award.
“The outcome of the arbitration vindicates Ghana’s position that every company operating in the country, regardless of its size, is subject to the laws of Ghana.”
Dr Cassiel Ato Forson, Minister of Finance
The government’s interpretation therefore places the ruling within a wider fiscal context: the state is seeking to enforce tax obligations arising from petroleum operations while maintaining an investment relationship with one of Ghana’s principal upstream producers.
Tax Enforcement Meets Petroleum Investment
The case illustrates a recurring tension in resource-producing economies.
Ghana needs to collect revenues generated from its petroleum sector, particularly where tax authorities determine that taxable income has arisen.
At the same time, the country depends on international oil companies to continue financing exploration, field development, production and infrastructure.
That makes the handling of a tax dispute involving a major producer more consequential than the immediate value of the assessment.
Tullow remains a significant participant in Ghana’s upstream industry, with interests in the Jubilee and TEN fields.
The government’s own response to the tribunal’s decision acknowledges the importance of maintaining the company’s capacity to continue investing in those assets.
This creates a balancing exercise for policymakers. Securing assessed revenue is one objective; ensuring that the mechanism used to recover it does not unnecessarily disrupt ongoing petroleum operations is another.
The government has indicated that it intends to work within Ghanaian law while considering the continuity of Tullow’s operations and its capacity to sustain investment.
“In implementing the award, Government will have due regard to the continuity of operations in the Jubilee and TEN fields and Tullow’s capacity to sustain the investments required in those fields.”
Dr Cassiel Ato Forson, Minister of Finance
That position suggests that the government’s approach is not simply about establishing the tax liability, but also about managing the economic consequences of its enforcement.
A Relationship Ghana Still Needs To Manage
Despite the arbitration dispute, both sides have left room for continued engagement.
The Finance Minister said discussions between the government and Tullow had already begun before the tribunal delivered its award and would continue. Those discussions are expected to cover the matter determined by the tribunal as well as separate outstanding tax proceedings.
For Ghana, this matters because petroleum production is not static. Existing fields require continued investment to sustain output, particularly as the country’s producing assets mature and pressure grows to maintain production levels.
The government has therefore framed the relationship with Tullow as one that must accommodate both fiscal accountability and continued petroleum investment.
Tullow’s response is similarly restrained. Rather than announcing a new dispute, the company has said it will consider its next steps after further discussions with government.
That leaves the post-award phase focused less on the tribunal’s conclusion, which has now been delivered, and more on the practical consequences of implementing it.
The ruling also provides a clear outcome on the particular contractual question placed before the tribunal: the US$196.5 million tax assessment was not found to violate Tullow’s Petroleum Agreements.
For Ghana’s petroleum sector, the wider significance lies in what happens next. The state has secured a favourable arbitration outcome, but the financial value of that outcome will ultimately depend on implementation, while the industry’s productive value will depend on maintaining investment and output from the fields involved.
The challenge is therefore no longer simply the legal dispute. It is how Ghana converts the tribunal’s decision into public revenue without undermining the investment and production activity that continues to support the country’s upstream petroleum sector.
READ ALSO: Spanish Government Loses Parliamentary Backing For Housing Measures