

Ghana’s banking industry is facing a changing fraud threat as criminals increasingly abandon attempts to break into banking systems and instead exploit the trust customers place in people they believe are legitimate financial service representatives.
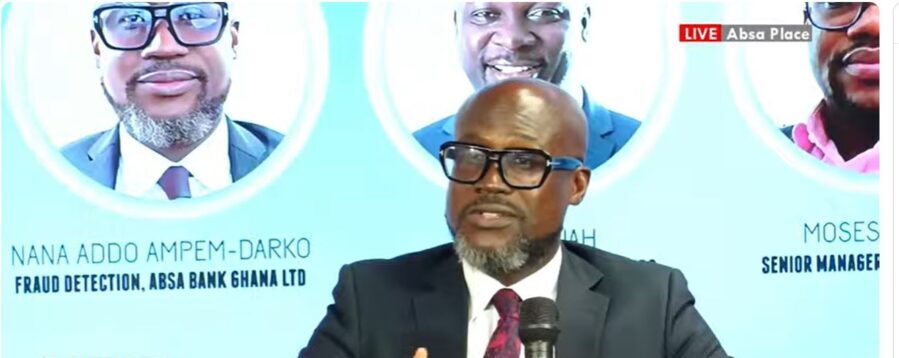
Absa Bank Ghana Limited’s fraud detection expert, Nana Addo Ampem-Darko, has warned that social engineering has emerged as one of the biggest threats to digital financial security, with fraudsters manipulating customers into surrendering confidential banking information or authorising transactions themselves.
The warning comes as financial institutions continue to invest in technology to strengthen their security systems and protect customers against unauthorised access. However, these improvements are also changing how criminals approach their targets, shifting attention towards the human beings behind banking transactions.
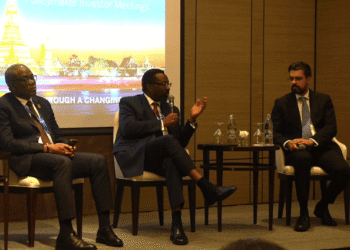
Speaking at the 14th Absa-UPSA Law School Quarterly Banking Roundtable, Mr Ampem-Darko explained that fraudsters were increasingly exploiting human behaviour because penetrating the security systems of banks and other financial service providers had become more difficult.
“Today, our biggest challenge is social engineering. It’s what we call human hacking, analysing human behaviour,” he said.
His remarks highlight a growing concern for Ghana’s digital financial sector, where the expansion of electronic banking and digital transactions has made convenience increasingly important while exposing customers to sophisticated forms of deception.
Fraudsters Find a New Route Around Bank Security
Banks have strengthened their technological defences to detect suspicious transactions, prevent unauthorised access and protect sensitive customer information. Yet, according to Mr Ampem-Darko, stronger systems have not eliminated the threat of financial fraud.
Instead, criminals are increasingly targeting the people who use these systems.
Rather than attempting to defeat sophisticated banking infrastructure, fraudsters may pose as legitimate representatives, create convincing stories and gradually gain the confidence of unsuspecting customers.
Once trust has been established, victims may be persuaded to disclose usernames, passwords and one-time passwords (OTPs), giving criminals information they need to access accounts or initiate transactions.
This approach creates a difficult situation for banks because the transactions may involve credentials or approvals supplied directly by the customer.
In such cases, distinguishing a fraudulent transaction from a legitimate one becomes more complicated, particularly when the customer believes they are following genuine instructions to protect their account.
The development also exposes a weakness that technological investment alone cannot completely eliminate. Even when a bank’s systems are functioning as intended, a customer can still be manipulated into providing access to a fraudster.
GH¢700,000 Fraud Attempt Reveals the Stakes
Mr Ampem-Darko illustrated the danger by recounting an incident involving a customer who was deceived into setting up internet banking and sharing his login credentials and OTPs with fraudsters.
The criminals allegedly presented themselves as people helping to protect the customer’s account, using the promise of security to persuade him to disclose sensitive information.
What appeared to be assistance ultimately opened the door to a potentially costly financial loss.
According to the fraud detection expert, the fraudsters subsequently attempted transactions worth more than GH¢700,000 within approximately two hours.
The scale and speed of the attempted transactions demonstrate how quickly a carefully orchestrated deception can escalate into a serious financial threat.
Fortunately, the bank and its partners detected the suspicious activity and blocked the account, preventing further losses.
The incident illustrates the importance of transaction monitoring and cooperation between financial service providers. It also shows why customers must exercise caution when anyone requests confidential banking information, regardless of how convincing their explanation may sound.
Although the attempted transactions were detected, the episode exposes the financial risks that can arise when criminals successfully manipulate customers into compromising their own security.
Customer Trust Becomes a Major Vulnerability
Beyond the attempted transactions, Mr Ampem-Darko identified misplaced trust as a central challenge confronting banks and their customers.
“If you ask me today, our biggest threat is actually our trust. The fact that we trust people and then we tend to give them access to our systems.”
Ampem-Darko
The concern is particularly relevant in an environment where customers routinely receive calls, messages and other communications from institutions offering financial services.
Fraudsters can exploit these familiar interactions by pretending to represent banks, creating a sense of urgency or claiming that immediate action is necessary to prevent an account from being compromised.
A customer who believes they are responding to a security emergency may unknowingly provide the very information a criminal needs to carry out a fraudulent transaction.
The challenge, therefore, extends beyond the technology used to secure accounts. It also involves customer awareness, the ability to recognise suspicious requests and the willingness to verify claims before taking action.
As digital banking becomes more widespread, these precautions are increasingly important in protecting personal finances.
Banks Urged to Strengthen Monitoring and Collaboration
Mr Ampem-Darko stressed the importance of collaboration among financial service providers and continued transaction monitoring to identify and prevent fraudulent activities.
Such cooperation can help institutions recognise suspicious patterns, respond to emerging threats and intervene before fraudulent transactions result in significant losses.
Continuous monitoring is particularly important when transactions occur rapidly or display patterns that differ from a customer’s usual banking behaviour.
However, banks cannot carry the entire responsibility for preventing social engineering attacks. Customers also have a critical role in ensuring that their banking information remains confidential.
Mr Ampem-Darko urged customers to remain vigilant and avoid sharing confidential banking information, including with individuals who claim to be calling on behalf of their banks.
Customers should independently verify suspicious calls and requests through their bank’s official communication channels rather than relying on the contact details or instructions provided by an unknown caller.
They should also keep their passwords and OTPs private and avoid authorising transactions they do not fully understand.
Digital Banking Security Requires a United Effort
The growing reliance on digital financial services makes the fight against fraud increasingly important to Ghana’s banking industry.
As institutions strengthen their technological defences, criminals are demonstrating a willingness to exploit the human relationships that underpin financial services.
The warning from Absa’s fraud detection expert points to a threat that cannot be addressed through sophisticated software alone. Effective protection requires secure banking systems, vigilant customers, reliable transaction monitoring and stronger collaboration across the financial sector.
The GH¢700,000 attempted fraud serves as a reminder that a convincing conversation can become the starting point of a serious financial crime.
Ultimately, protecting bank accounts requires customers to question unexpected requests, verify identities and safeguard confidential information. Trust remains important in financial services, but it must be accompanied by caution, particularly when someone asks for access to money or sensitive banking credentials.
READ ALSO: Mahama Breaks Ground for 1,238-acre Afienya Industrial Park