
Ghana’s monetary policy has taken another dramatic turn after the Bank of Ghana (BoG) announced a massive 300-basis-point reduction in the Monetary Policy Rate, bringing it down from 14 per cent to 11 per cent.
The decision, announced on November 18, 2026, represents a significant easing of monetary policy and could provide fresh relief to businesses, households and investors grappling with borrowing costs.
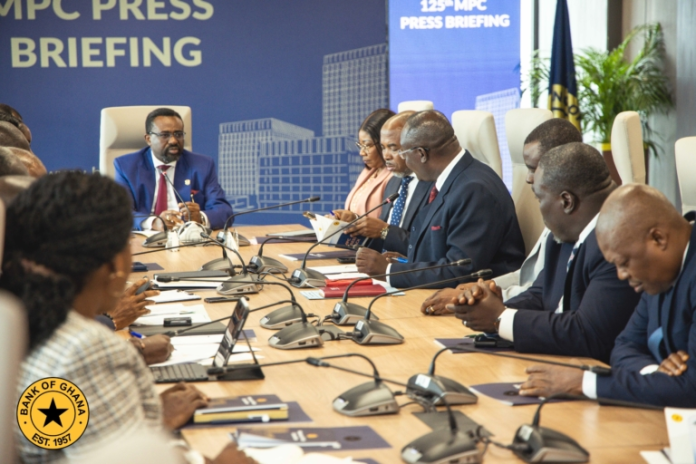
Governor of the Bank of Ghana, Dr Johnson Asiama, announced the reduction following the 133rd Monetary Policy Committee (MPC) meeting held from November 16 to 18, 2026.
The latest cut comes against the backdrop of improving domestic economic conditions, stronger private sector credit growth and declining commercial bank lending rates. It also signals growing confidence among policymakers that inflationary pressures remain sufficiently contained to support further monetary easing.
However, with inflation recording a marginal increase in October and international reserves declining from their December 2025 levels, the central bank’s latest decision comes with important economic considerations.
BoG Delivers Another Major Blow to Borrowing Costs
The reduction of the policy rate to 11 per cent marks a substantial shift in the central bank’s monetary policy direction.
By cutting the rate by 300 basis points, the MPC has lowered the benchmark at which monetary policy influences interest rates across the financial system.
The development could strengthen the ongoing decline in lending rates and create more favourable financing conditions for businesses seeking capital to expand their operations.
Explaining the committee’s decision, Dr Asiama said domestic economic activity had continued to improve, supported by stronger credit conditions and increased lending to the private sector.
“Taken together, the Committee noted significant improvements in domestic macroeconomic conditions. Domestic growth has remained firm, supported by easing credit conditions and expansion of private sector credit, and is expected to continue for the remainder of the year.”
Dr Johnson Asiama
The Governor’s remarks suggest that the central bank is increasingly comfortable with the direction of economic activity and believes the prevailing conditions can accommodate a lower policy rate.
Lending Rates Fall as Credit Growth Accelerates
One of the strongest arguments supporting the latest reduction is the remarkable improvement in private sector credit growth.
Growth in private sector credit increased to 37.2 per cent in October 2026, compared with 13.9 per cent recorded during the corresponding period in 2025.
Even more significantly, real private sector credit growth, which accounts for the effect of inflation, climbed to 30 per cent from 5.4 per cent over the same period.
These figures indicate that businesses and households are accessing significantly more credit than they did a year earlier.
Commercial banks have also begun reducing their lending rates, providing further evidence of easing financing conditions.
Average lending rates declined to 15.8 per cent in October 2026 from 22.2 per cent in October 2025.
The latest policy rate reduction could accelerate this downward movement, although the extent and speed of any additional reduction in commercial lending rates will depend on banks’ funding costs, risk assessments and competitive conditions.
Businesses that have struggled with expensive loans could find some breathing room if the reduction is transmitted effectively through the banking system.
BoG Reshapes Its Monetary Operations Framework
Beyond the headline rate reduction, the central bank is introducing significant changes to the framework through which it manages liquidity and influences market interest rates.
Dr Asiama explained that prevailing market interest rates had already fallen below the existing policy rate of 14 per cent, suggesting that the effective monetary policy stance was less restrictive than the headline rate indicated.
He attributed the improvement partly to reforms introduced to strengthen the transmission of monetary policy decisions.
“Recent reforms to the Bank’s monetary operations framework have strengthened liquidity management and improved the transmission of monetary policy signals to money market rates.”
Dr Johnson Asiama
The MPC has consequently introduced additional reforms, including replacing the existing open market operations instrument with a seven-day instrument.
It has also narrowed the monetary policy corridor from plus or minus 400 basis points to plus or minus 100 basis points around the policy rate.
These adjustments are expected to improve the effectiveness of monetary policy implementation and strengthen the relationship between the policy rate and short-term money market interest rates.
The changes could become particularly important as the central bank attempts to ensure that its policy decisions translate more efficiently into actual financing conditions across the economy.
Inflation Rises Slightly Despite Major Rate Cut
Despite the aggressive monetary easing, inflation remains an important consideration.
Headline inflation increased marginally to 5.5 per cent in October 2026 from 5.2 per cent in September.
Although the increase represents a reversal of the previous month’s movement, inflation remains below the lower bound of the Bank of Ghana’s medium-term target range.
The central bank expects inflation to gradually return to its target range over the medium term.
However, it has identified several risks that could complicate the inflation outlook.
These include potential crude oil price shocks, the impact of El Niño on food production and quarterly adjustments in utility tariffs.
Such developments could introduce fresh price pressures, particularly if they affect transportation, electricity, agricultural production and the cost of essential goods and services.
The MPC will therefore have to balance the need to support economic growth with the responsibility of preserving the inflation gains achieved over recent months.
International Reserves Present Another Concern
While domestic economic conditions have improved, Ghana’s external position presents another important consideration.
Gross international reserves stood at US$12.1 billion as of November 17, 2026, equivalent to 4.4 months of import cover.
This represents a decline from US$13.8 billion recorded at the end of December 2025.
The reduction in reserves will remain an important factor in assessing the country’s external buffers, particularly as exchange rate stability and the ability to finance imports remain central to macroeconomic confidence.
The MPC’s decision to reduce the policy rate therefore comes at a time when policymakers must carefully manage both domestic growth and external vulnerabilities.
January Meeting Could Shape Ghana’s Interest Rate Outlook
The latest 300-basis-point reduction places Ghana’s policy rate at 11 per cent, marking another significant development in the country’s monetary policy direction.
Attention will now turn to how quickly commercial banks respond, whether lending rates decline further and how businesses translate improved credit conditions into investment and expansion.
The central bank’s next Monetary Policy Committee meeting is scheduled for January 2027.
By then, developments in inflation, exchange rate stability, international reserves and private sector activity could provide a clearer indication of whether Ghana’s monetary easing cycle has further room to continue.
READ ALSO: Minority Describes Government’s Economy Progress As “Artificial”