Government says longstanding regulatory and fiscal weaknesses in Ghana’s petroleum sector weakened investor confidence and contributed to some major international oil companies scaling back or shifting capital to competing markets, as authorities prepare a new round of upstream reforms.
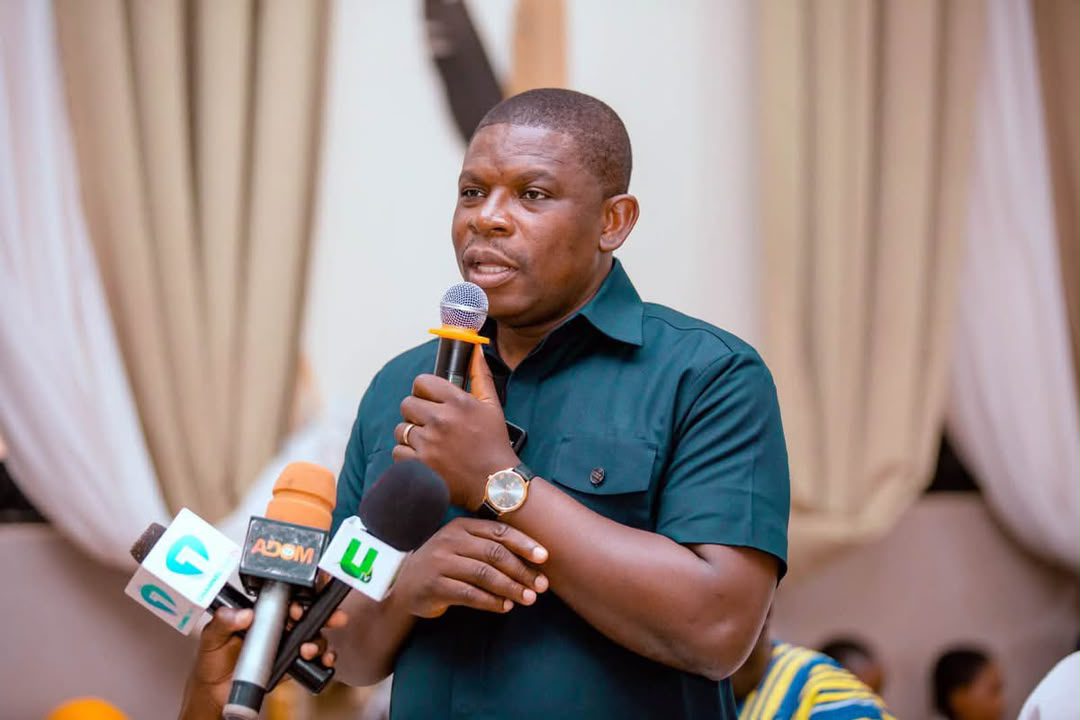
The admission came from Deputy Minister for Energy and Green Transition Richard Gyan-Mensah, who said government is now using recommendations from its Upstream Reform Committee to address long-standing concerns around the fiscal regime, regulatory environment and broader investment framework governing oil and gas exploration and production.
Speaking at the Africa Business Conversation organised by AB & David Africa under the theme “From Investor Interest to Committed Capital: How to Reset Ghana’s Petroleum Upstream Sector for Sustainable Investments,” the Deputy Minister said Ghana can no longer assume that investor interest automatically translates into actual investment.
We also recognise that legacy issues created uncertainty within the sector and contributed to some of the world’s leading international oil companies reducing or redirecting investment elsewhere.
Deputy Minister for Energy and Green Transition, Richard Gyan-Mensah
His remarks come at a critical moment for Ghana’s upstream industry, which has experienced declining crude oil production, slower exploration activity and increasing competition from other African petroleum jurisdictions seeking to attract a shrinking pool of global upstream investment.
A rare official admission
For years, industry analysts have argued that Ghana’s upstream sector was becoming less competitive due to delays in approvals, uncertainty over fiscal terms, contract management issues and concerns about the overall cost of doing business.
What makes the Deputy Minister’s comments significant is that government is no longer treating those concerns as external criticism but as factors that materially affected investment decisions.
The acknowledgement suggests a shift in official thinking, from defending the existing framework to accepting that structural reforms are necessary if Ghana is to regain momentum in exploration and production.
The statement also aligns with broader government efforts to reverse the sharp decline in crude oil output recorded over recent years.
From interest to committed capital
According to the Deputy Minister, government has already engaged industry players to resolve some of the outstanding issues, and several global energy companies have expressed renewed interest in Ghana’s upstream sector, as first reported by cities news.
However, he cautioned that expressions of interest are not enough.
Capital is committed only where there is regulatory certainty, competitive fiscal terms, a business-friendly environment, reliable data and the infrastructure needed to bring discoveries to market.
Deputy Minister for Energy and Green Transition, Richard Gyan-Mensah
The distinction is important.
In the upstream industry, companies often show interest in acreage, participate in discussions or review data without committing significant capital.
Actual investment decisions are typically made only when investors have confidence that projects can generate acceptable returns over long time horizons.
For Ghana, the challenge is therefore not attracting attention but securing final investment decisions.
The Upstream Reform Committee takes centre stage
Mr. Gyan-Mensah disclosed that government has received the report of the Upstream Reform Committee, which contains recommendations aimed at improving Ghana’s competitiveness, reducing business costs and strengthening investor confidence.

Although he did not publicly detail the recommendations, the reference suggests that reforms could touch on fiscal terms, licensing processes, regulatory coordination, data access and project approvals.
The next test will be implementation.
Ghana has produced several energy sector reform reports over the years, but investors will be watching to see whether the current recommendations lead to concrete legislative, fiscal and administrative changes rather than remaining policy proposals.
Why the timing matters
The reform push comes as global upstream capital becomes increasingly selective.
International oil companies are under pressure to improve returns, reduce emissions and allocate capital more carefully across competing jurisdictions.
African producers are therefore competing not only with one another but also with opportunities in Latin America, the Middle East and established producing regions.
Ghana’s challenge is compounded by the maturity of some of its producing fields.
Declining production means new exploration and development activity is needed to sustain output, maintain government revenue and preserve the role of the petroleum sector in the wider economy.
Without fresh investment, the risk is not only lower oil production but also reduced gas availability for power generation and weaker foreign exchange earnings.
The real problem may be confidence, not geology
One of the most important signals from the Deputy Minister’s remarks is that government does not appear to be questioning Ghana’s geological potential.
The issue is confidence.
Investors generally know that Ghana remains part of a proven hydrocarbon basin with established production infrastructure and significant technical expertise.
The concern is whether the commercial and regulatory environment is sufficiently predictable to justify multi-billion-dollar investments.
This is where the conversation becomes broader than petroleum.
Regulatory certainty, contract stability, dispute resolution, payment discipline and institutional coordination are issues that affect the entire investment climate.
If government can improve those areas in the upstream sector, the benefits could extend beyond oil and gas.
A necessary reset, but not a guaranteed recovery
Government deserves credit for acknowledging the problem.
Admitting that legacy issues contributed to the loss or redirection of investment is an important first step, and the emphasis on regulatory certainty and competitive fiscal terms is consistent with what investors have been demanding.
But recognition is not recovery.
The harder question is whether Ghana is prepared to make the trade-offs that meaningful reform may require.
More competitive fiscal terms could reduce government take in the short term.
Faster approvals may require institutional restructuring.
Greater certainty may demand stronger protection of contractual commitments across political cycles.
These are not technical adjustments; they are governance choices.
What investors will watch next
The market will likely focus on three immediate signals: whether government publishes the key recommendations of the Upstream Reform Committee, whether proposed reforms are translated into legislation, regulations or revised fiscal terms, whether any major international oil company announces a new exploration, appraisal or development commitment in Ghana.
A credible reform process would probably involve transparent consultation with industry, Parliament and regulators, as well as clear timelines for implementation.
The stakes for Ghana’s energy future
The debate is ultimately about more than attracting oil companies.
Upstream investment affects government revenue, foreign exchange inflows, employment, local content opportunities and gas supply for electricity generation.
A weaker upstream sector can therefore create pressure across the broader energy and fiscal landscape.
The Deputy Minister’s remarks suggest government understands that the window for action may be narrowing.
Ghana still has proven resources, existing infrastructure and a track record of commercial production.
But in a world of increasingly mobile capital, those advantages are no longer sufficient on their own.
If the current reform effort succeeds, Ghana could begin rebuilding its reputation as one of West Africa’s more attractive upstream destinations.
If it stalls, renewed investor interest may remain exactly that, interest, not committed capital.
READ MORE: Ecobank Profit Soars to US$423 Million