
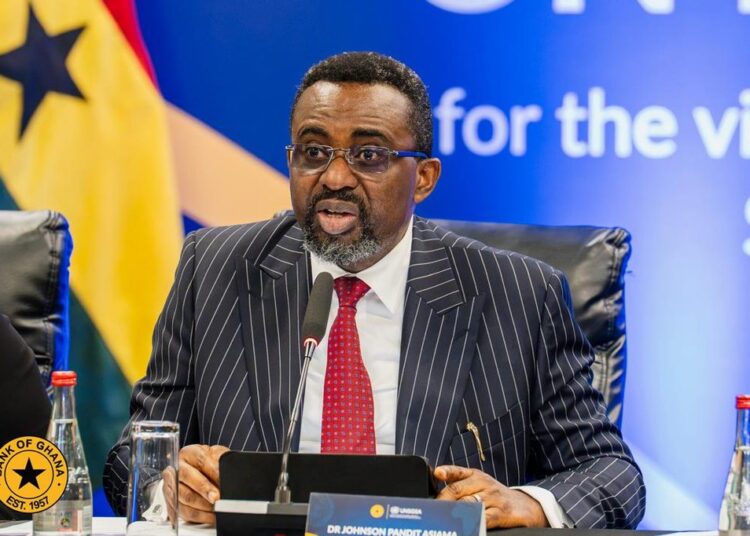
Ghana’s banking sector is facing a fresh challenge as the Bank of Ghana (BoG) Governor, Dr Johnson Pandit Asiama, calls on financial institutions to place ethics, accountability and responsible leadership at the centre of their digital transformation strategies.
As banks accelerate investments in artificial intelligence, mobile banking, fintech partnerships and other emerging technologies, the Governor is warning that technological advancement without strong ethical foundations could expose institutions to serious risks, undermine customer confidence and threaten financial stability.
The warning comes at a time when digitalisation is rapidly changing how financial services are delivered, creating opportunities for greater financial inclusion while introducing increasingly sophisticated threats to cybersecurity, customer privacy and institutional governance.
Speaking through the Bank of Ghana’s Director of Communications, Bernard Otabil, who delivered the address on his behalf, Dr Asiama argued that technology alone cannot guarantee a sustainable future for the banking industry.
Addressing participants at a conference held under the theme, “Banking on the Future: Trust, Technology and Transformation”, the Governor stressed that trust, technological advancement and institutional transformation must progress together.
His intervention places renewed pressure on banks to reconsider how they develop digital products, manage customer information and protect their institutions against emerging threats.
Ghana’s Banking Crisis Offers a Costly Lesson
The Governor’s warning draws attention to Ghana’s financial-sector clean-up between 2017 and 2019, a period that exposed serious weaknesses in corporate governance and institutional accountability.
The exercise resulted in the collapse of several financial institutions, with poor corporate governance, insider dealings, weak risk management and unethical conduct by some directors and senior managers identified among the contributing factors.
Dr Asiama believes the experience should serve as a permanent reminder that financial institutions cannot rely on capital adequacy, liquidity positions or sophisticated technology alone to guarantee their survival.
“A bank can have adequate capital, liquidity and sophisticated technology, but if its leadership lacks integrity and its internal controls are compromised, the institution remains fundamentally vulnerable.”
Dr Asiama
The observation raises an important concern as banks increasingly compete to introduce sophisticated digital platforms while potentially overlooking the governance structures needed to protect customers and shareholders.
The Governor is effectively challenging bank boards and executives to ensure that ethical leadership is embedded in their institutions rather than treated as a regulatory obligation.
Cybersecurity Threats Expose Banks to New Vulnerabilities
Beyond governance failures, the Bank of Ghana is increasingly concerned about cybersecurity vulnerabilities that could expose financial institutions to attacks and compromise customer information.
The Governor’s address referenced the Bank’s 2025 Annual Report, which highlighted several security weaknesses across the financial sector.
These include inadequate safeguards for public-facing systems, weak security configurations, stolen login credentials and the takeover of active user sessions.
Such vulnerabilities demonstrate that cyberattacks are not always the result of sophisticated criminal operations. Weak internal controls, inadequate staff training and poor management oversight can create opportunities for criminals to penetrate banking systems.
The Bank of Ghana has established a Financial Industry Command Security Operations Centre to strengthen the industry’s collective response to cyber threats.
According to the address, the facility provides threat intelligence to 23 banks, helping institutions identify and respond to emerging security risks.
However, the Governor insists that shared cybersecurity infrastructure cannot replace individual banks’ responsibility to invest in secure systems, strengthen internal controls and train employees to recognise suspicious activities.
Boards and senior executives must also take direct responsibility for cybersecurity rather than leaving the issue entirely to information technology departments.
AI and Customer Data Raise Ethical Questions
Artificial intelligence is opening new opportunities for banks to improve operational efficiency, detect fraud and assess credit risks. However, its growing influence in financial decision-making is creating concerns about fairness, privacy and accountability.
Dr Asiama cautioned that banks must pay particular attention to how customer information is collected, processed and used.
The growing reliance on personal data for customer profiling, credit assessment and automated decision-making raises questions about privacy, consent and confidentiality.
There is also the possibility that poorly designed artificial intelligence systems could produce biased outcomes, unfairly disadvantage certain customers or expose sensitive information.
A customer denied a loan through an automated system should not be left without an explanation simply because the decision was generated by an algorithm.
The Governor therefore wants ethical considerations incorporated into technology from the beginning of product development rather than introduced after services have already reached customers.
This approach could become increasingly important as Ghanaian banks deepen their reliance on digital platforms and automated financial services.
Virtual Assets Bring Another Regulatory Challenge
The growing popularity of cryptocurrencies, stablecoins and tokenised financial products presents another area requiring careful attention from banks and regulators.
While these innovations could create opportunities for financial inclusion and economic development, they also introduce risks involving money laundering, terrorist financing, cyber vulnerabilities and market abuse.
The Governor identified the Virtual Asset Service Providers Act, 2025 (Act 1154), as an important foundation for regulating the evolving virtual asset ecosystem.
The challenge will be ensuring that regulatory safeguards keep pace with innovation without unnecessarily restricting services that could benefit customers and the wider economy.
Banks must therefore strike a balance between embracing emerging technologies and protecting the integrity of the financial system.
BoG Places Responsibility on Bank Executives
Although the Bank of Ghana intends to continue strengthening its supervisory approach to digital finance, cybersecurity and financial crime, Dr Asiama believes regulators cannot shoulder the entire responsibility for ethical banking.
“No supervisory framework can replace the responsibility of institutions to act with integrity,” the Governor said.
The statement places significant responsibility on boards and senior management to establish strong ethical cultures, effective compliance systems and sound risk management practices.
It also challenges banks to move beyond the traditional pursuit of short-term profitability and embrace sustainable value creation.
Ultimately, Ghana’s banking future will depend on more than the speed at which financial institutions introduce new technologies. Their ability to protect customer information, manage risks, maintain accountability and uphold public confidence will be equally important.
Digital transformation promises a more accessible and efficient banking system. But without ethical leadership and responsible governance, the same technology intended to strengthen financial institutions could become a source of serious vulnerability.
READ ALSO: StoryFest Ghana Debuts as National Creative Festival