
Ghana’s banking sector is facing tighter scrutiny over fraud management as the Bank of Ghana (BoG) moves to give fraud units greater independence and a direct line to the highest levels of bank management.
The central bank has directed banks to ensure that their fraud management functions have direct and unrestricted access to managing directors and chief executive officers.
The directive places fraud management closer to the centre of corporate decision-making at a time when banks are dealing with increasingly sophisticated forms of financial crime, cyber threats and technology-related risks.
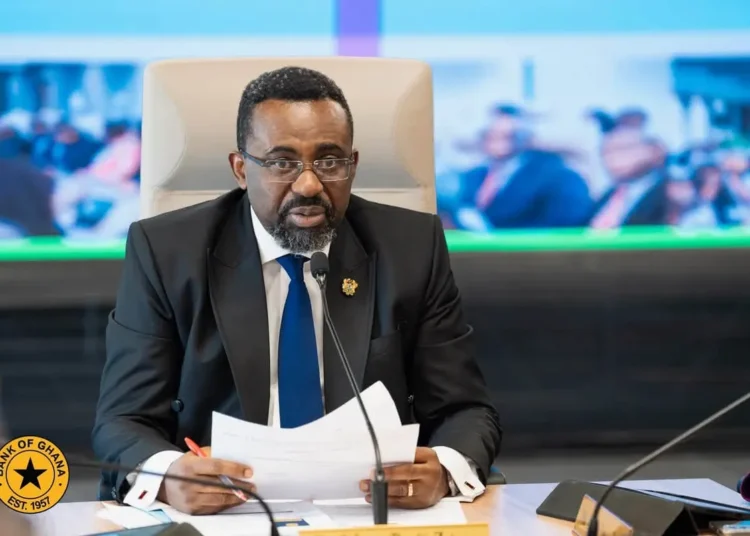
Speaking at a meeting with the heads of banks, BoG Governor Dr Johnson Asiama said the central bank had received concerns from the Ghana Association of Banks regarding the different ways fraud functions are currently positioned within financial institutions.
He described fraud as a significant risk that requires serious attention from the banking industry.
Fraud Chiefs Get Direct Access to Bank CEOs
At the heart of the directive is the demand for stronger independence for fraud management teams.
Dr Asiama said banks must ensure that their fraud functions are positioned in a manner that allows them to escalate serious concerns without unnecessary internal barriers.
“The fraud function should be appropriately positioned with direct and unrestricted access to the managing director or chief executive officer.”
The requirement could significantly change how some banks structure their internal fraud controls.
Rather than having fraud-related concerns filtered through several layers of management, the new arrangement is designed to give responsible officers the ability to raise critical issues directly with senior executives.
That access could prove important when suspected fraudulent activity involves senior personnel, major transactions or weaknesses that require immediate intervention.
The BoG expects the arrangement to strengthen both the independence and effectiveness of fraud management functions across banks.
BoG Raises Standards for Fraud Professionals
The central bank is also looking beyond organisational structures.
Dr Asiama directed banks to ensure that personnel responsible for fraud management possess the skills and professional qualifications required to perform their roles effectively.
This includes appropriate professional certifications and technical competence.
The emphasis reflects the changing nature of financial fraud. Criminal activity affecting banks is no longer limited to traditional schemes involving forged documents or unauthorised transactions.
Digital banking, mobile applications, electronic payments and interconnected financial platforms have created new opportunities for criminals to exploit weaknesses in systems and processes.
Fraud teams therefore need technical knowledge that matches the sophistication of the risks confronting financial institutions.
Banks will increasingly need personnel who can identify unusual transactions, investigate suspicious activity, understand digital vulnerabilities and respond quickly when fraud incidents emerge.
The BoG’s directive signals that having a fraud department alone will not be enough. Banks must ensure that the function is properly empowered and staffed with competent professionals.
Digitalisation Creates New Risks
The renewed focus on fraud comes as Ghana’s financial sector continues its rapid shift towards digital services.
Customers now depend heavily on electronic channels to transfer money, make payments, access accounts and conduct other financial transactions.
Digitalisation has improved convenience and expanded access to financial services, but it has also created additional points of vulnerability.
Dr Asiama said the BoG is paying increased attention to cyber technology and fintech-related risks as these developments reshape the financial sector.
He acknowledged the benefits of digitalisation while pointing to the operational and cyber risks that accompany it.
The challenge for banks is therefore becoming more complex. Institutions must protect customers and their funds while maintaining reliable digital systems capable of handling increasing transaction volumes.
A weakness in technology can quickly become a financial risk when thousands of customers depend on the affected platform.
Cybersecurity Moves Higher Up the Agenda
The BoG is also working with the banking industry on the implementation of the Cyber and Information Security Directive.
The central bank intends to strengthen its supervisory expectations around technology, customer-fund safeguarding and third-party risks.
This is particularly important as banks increasingly depend on technology providers and external service partners to deliver financial products and maintain critical systems.
Third-party vulnerabilities can expose financial institutions to risks beyond their immediate control. A weakness in a service provider’s system could potentially affect a bank’s operations, customer information or ability to deliver services.
The BoG’s approach therefore appears increasingly focused on the broader ecosystem supporting financial services, rather than only the internal systems of individual banks.
Banks Face Greater Accountability
The new requirements could place additional responsibility on bank boards and senior management to ensure that fraud controls operate effectively.
Giving fraud units direct access to CEOs means senior executives can no longer be distant from serious concerns raised by those responsible for detecting and managing fraud risks.
At the same time, requiring professionally qualified and technically competent fraud personnel raises the standard expected of banks.
The developments come at a sensitive point for Ghana’s banking industry, where customer confidence remains closely tied to the security of financial transactions.
Fraud incidents can cause direct financial losses, but their impact can extend further by damaging trust in banks and digital financial services.
The BoG’s latest directive therefore puts fraud management firmly within the broader conversation about financial stability, cybersecurity and responsible banking.
As Ghana’s financial system becomes more digital, banks will have to strengthen their defences at the same pace. The latest BoG directive makes senior management access, professional competence and stronger internal controls central to that effort.
READ ALSO: Trump Links Student Protests In France To Migration