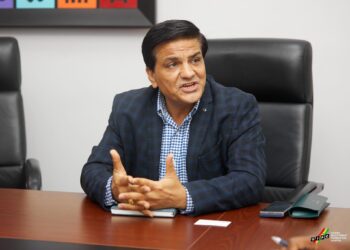

Loan defaults in Ghana’s microcredit sector have come under renewed scrutiny, with the National Board Chairperson of the Micro Credit Association Ghana, Benjamin Turkson Junior, blaming weak borrower assessment and inadequate risk management systems among some lending institutions for contributing to the problem.
Mr Turkson has challenged microcredit institutions and other financial service providers to rethink how they evaluate loan applicants, warning that poor lending decisions can expose financial institutions to avoidable losses and undermine the sustainability of their operations.
His remarks highlight a critical weakness in the lending business, where financial institutions must strike a delicate balance between expanding access to credit and ensuring that borrowers have the financial capacity and willingness to repay their loans.
According to him, lenders cannot simply advance credit to applicants without conducting proper assessments and then place the entire responsibility for repayment failures on customers.
He believes that stronger risk management practices could significantly reduce defaults by helping institutions distinguish between borrowers who can meet their obligations and those who may struggle to repay.
‘We Don’t Have Bad Borrowers, But Bad Lenders’
Mr Turkson offered a pointed assessment of the relationship between lending practices and loan defaults, arguing that financial institutions must take greater responsibility for the quality of their credit decisions. “I have always personally developed a philosophy where I say we don’t have bad borrowers, but we have bad lenders,” he said.
The statement challenges a common perception within the financial services industry that borrowers are primarily responsible whenever loans become distressed.
Although his position does not absolve customers of their repayment obligations, it places considerable emphasis on the responsibility of lenders to establish whether prospective borrowers are suitable candidates for credit before approving facilities.
A financial institution that fails to examine a customer’s income, existing financial commitments, repayment capacity and borrowing history could end up extending credit to individuals whose circumstances make repayment difficult.
Mr Turkson maintained that institutions with effective risk management systems are better positioned to avoid such situations and protect their loan portfolios. “If your risk management framework is very solid, definitely you are going to get good clients to lend to them,” he said.
His comments come at a time when credit providers must remain vigilant about the quality of their lending decisions, particularly as they seek to serve individuals and businesses that depend on microcredit to finance their activities.
Borrowers Cannot Escape Repayment Responsibilities
Despite placing significant responsibility on lenders, the Micro Credit Association Ghana chairperson acknowledged that some customers deliberately refuse to repay loans even when they have the capacity to do so.
He stressed that the lending industry operates through a relationship of mutual dependence, where financial institutions need customers to sustain their businesses, while borrowers rely on lenders to access funding. “We are an ecosystem where we need each other to survive. We need the customers. The customers also need us,” he said.
This relationship, he explained, makes repayment discipline essential to the survival of microcredit institutions.
When customers fail to honour their repayment obligations, lenders lose access to funds that could otherwise be recycled into new loans for other individuals and businesses.
Persistent defaults can also place pressure on institutional cash flows, restrict lending capacity and increase the cost of managing distressed credit facilities.
The consequences can extend beyond individual institutions, potentially affecting access to financing for customers who genuinely need credit to support their economic activities.
Mr Turkson’s position therefore calls for responsibility on both sides of the lending relationship, with financial institutions expected to improve their assessment processes and borrowers required to honour the commitments they make when accessing credit.
Credit Reference Bureaus Could Become Defaulters’ Biggest Obstacle
Another important intervention proposed by Mr Turkson is the increased use of credit reference bureaus licensed by the Bank of Ghana.
He urged lending institutions to make borrower credit histories an integral part of their loan approval processes, arguing that these records provide valuable information about applicants’ previous borrowing and repayment behaviour.
Credit reference bureaus collect and maintain information that helps financial institutions evaluate the creditworthiness of prospective customers.
By checking these records before approving loans, lenders can identify applicants with histories of unpaid facilities and make more informed decisions about the risks associated with extending additional credit.
Mr Turkson also encouraged financial institutions to consistently submit relevant borrower information to the licensed bureaus to strengthen the reliability and usefulness of the credit reporting system.
He warned that customers who deliberately default on loans could face difficulties accessing financing from other institutions because their repayment records may follow them across the financial system.
“If you are planning to take a loan and not pay, then know that your next facility you are not going to get it because your records will be out there,” he cautioned.
The warning carries significant implications for borrowers who assume that defaulting on a facility with one institution will have no consequences when they approach another lender.
A more comprehensive credit reporting system could make it increasingly difficult for habitual defaulters to secure new financing without addressing their outstanding obligations.
Lenders Urged to Pursue Legal Recovery Processes
Beyond improving loan assessments and strengthening credit information sharing, Mr Turkson has also called on financial institutions to exercise patience when customers encounter genuine repayment difficulties.
He encouraged lenders to pursue outstanding debts through established legal procedures rather than resorting to approaches that could create unnecessary disputes between institutions and their customers.
His recommendation recognises that not every repayment failure results from deliberate unwillingness to pay. Some borrowers may experience financial difficulties that affect their ability to meet agreed repayment schedules.
A measured approach could allow lenders to protect their financial interests while ensuring that customers are treated fairly throughout the recovery process. “I think we follow through the legal process to recover our loan, and that will bring peace to both the institution and the customers,” he added.
The call reinforces the importance of maintaining lawful and transparent debt recovery practices within the microcredit industry.
A Bigger Test for Ghana’s Microcredit Industry
Mr Turkson’s intervention raises important questions about the standards governing loan approvals, borrower assessment and debt recovery within Ghana’s microcredit sector.
As financial institutions continue providing credit to individuals and businesses, the effectiveness of their risk management systems will remain central to the sustainability of their operations.
Stronger credit assessments, consistent use of credit reference bureaus and responsible repayment behaviour could help reduce avoidable defaults and improve confidence in the lending industry.
The chairperson also appealed to lawmakers to understand the challenges facing the microcredit sector, highlighting the need for an environment that supports sustainable lending and protects the interests of both institutions and customers.
Ultimately, the ability of the industry to maintain a healthy lending environment will depend on whether lenders and borrowers recognise their shared responsibilities.
Financial institutions must become more disciplined in deciding who receives credit, while customers must understand that borrowing creates an obligation that cannot simply be ignored.
READ ALSO: Mahama Tells Putin: Ghana-Russia Ties Must Deliver Economic Benefits