
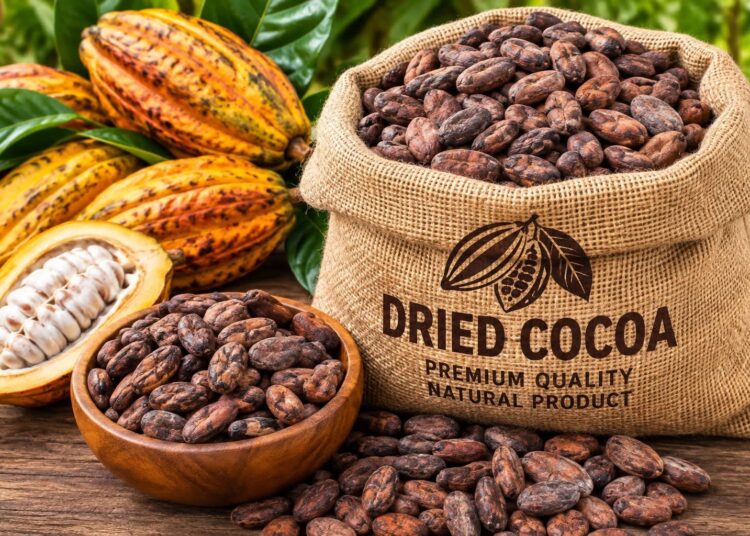
Global cocoa prices have come under renewed pressure following rising exchange inventories, increased export supplies from producing countries and uncertainty surrounding international demand, despite growing concerns about declining production in West Africa.
The contrasting market fundamentals have left cocoa futures fluctuating, with traders weighing immediate supply availability against the potential impact of adverse weather conditions on the 2026/27 crop season.
December New York cocoa futures (CCZ26) declined by 26 points, representing a 0.50 per cent fall, to close at the end of trading on Friday.
In contrast, December London cocoa futures (CAZ26) gained 19 points, equivalent to a 0.49 per cent increase, reflecting different trading pressures across the two international markets.
December ICE New York cocoa (CCZ26) closed down -26 (-0.50%) on Friday, and ICE London cocoa #7 (CAZ26) closed up +19 (+0.49%).
The mixed performance followed a broader decline that pushed cocoa prices to fresh five-week lows before both markets recovered from their lowest levels.
The immediate pressure has largely been associated with increasing cocoa inventories held by the Intercontinental Exchange (ICE), which have strengthened expectations of improved near-term supply availability.
Rising Inventories Intensify Market Pressure
ICE cocoa inventories have increased steadily since the beginning of the year, reaching 3,751,670 bags on Friday, their highest level in two and a half years.
The accumulation of stocks has eased concerns about immediate supply shortages, particularly as traders assess the availability of cocoa beans against expectations for global processing and consumption.
Currency movements have also influenced trading activity, particularly in the London cocoa market. The British pound weakened to a one-week low against the US dollar on Friday, encouraging traders to cover short positions in London cocoa futures.
A weaker pound generally makes cocoa priced in sterling more attractive to international buyers and can influence trading positions in the London market.
Meanwhile, developments in Brazil have introduced another bearish consideration for international cocoa prices. The Brazilian real recently weakened to a 10.25-month low against the US dollar following President Luiz Inácio Lula da Silva’s unexpected election victory.
The depreciation has raised expectations that Brazilian exporters could increase cocoa sales because dollar-denominated export earnings become more valuable when converted into the weaker local currency.
Although Brazil accounts for approximately four to five per cent of global cocoa production, according to International Cocoa Organization (ICCO) estimates, its position as the world’s seventh largest cocoa producer means changes in its export activity can influence international supply expectations.
Nigeria has also recorded increased export volumes. The country’s September cocoa bean exports rose by 33 per cent year-on-year to 19,343 tonnes, with higher international cocoa prices reportedly encouraging exporters to release more beans into the market.
El Niño Raises Production Concerns
Despite the immediate bearish pressures, longer-term supply concerns are providing some support to cocoa prices, particularly as weather forecasts point to potentially difficult growing conditions across major producing regions.
Commodity research firm StoneX has revised its outlook for the 2026/27 cocoa season, forecasting a global supply deficit of 64,000 metric tonnes, reversing its earlier projection of a 25,000 tonne surplus.
The revised outlook follows its estimated surplus of 494,000 tonnes for the 2025/26 season.
The projected decline is associated with the potential effects of El Niño, which typically brings warmer and drier conditions to parts of West Africa. Reduced rainfall and soil moisture can place cocoa trees under stress, affect pod development and ultimately lower yields.
The US Climate Prediction Center has indicated that the El Niño pattern emerging across the equatorial Pacific could become one of the strongest in more than 75 years, heightening concerns about agricultural production in weather-sensitive regions.
The country’s main crop harvest began this month, but preliminary estimates place production at approximately 1.8 million metric tonnes, representing an 18 per cent decline from the estimated 2.2 million tonnes recorded in 2025/26.
West African Supply Faces Growing Uncertainty
Côte d’Ivoire, the world’s leading cocoa producer, has already recorded a significant reduction in cocoa deliveries to its ports during the opening weeks of the current marketing season.
According to figures reported by Bloomberg, cumulative arrivals between October 1 and November 1 declined by 43 per cent year-on-year to 173,158 tonnes, down from 304,840 tonnes recorded during the comparable period.
Ivory Coast cocoa port arrivals fell -43% yr/yr to 173,158 MT from the comparable year-earlier figure of 304,840 MT.
The figures point to reduced supplies entering the international export market, although Côte d’Ivoire’s adjustment of its 2026/27 marketing calendar, which began on September 1 instead of October 1, remains an important consideration when interpreting shipment comparisons.
Ghana’s production outlook is equally important to international market expectations. As the world’s second-largest cocoa producer, the country remains a major determinant of global supply availability.
On August 20, the Ghana Cocoa Board (COCOBOD) estimated that the country’s 2026/27 cocoa production could reach 650,000 metric tonnes, representing a 13 per cent decline from the 750,000 tonnes recorded in the 2025/26 crop year.
However, an earlier projection issued by COCOBOD on July 30 placed potential production between 450,000 and 550,000 tonnes, citing swollen shoot disease, ageing cocoa farms and the anticipated effects of El Niño.
These concerns contrast with Ghana’s relatively strong performance in the preceding season, when the regulator reported on August 26 that production had reached 750,000 tonnes, up 25.6 per cent from 597,000 tonnes in 2024/25.
Meanwhile, international demand indicators have presented a mixed picture. The National Confectioners Association reported a 2.5 per cent year-on-year decline in North American third-quarter cocoa grindings to 109,978 tonnes.
Conversely, the Cocoa Association of Asia recorded a 29 per cent increase to a record 233,767 tonnes, while the European Cocoa Association reported a 3.2 per cent increase to 348,215 tonnes.
These contrasting figures suggest that demand conditions remain uneven across major consuming regions.
Ultimately, the cocoa market faces competing pressures from rising exchange inventories, increased export activity and uncertain consumption on one hand, and declining West African production prospects and potential El Niño-related disruptions on the other.
The direction of international cocoa prices will depend increasingly on how these supply and demand fundamentals develop throughout the 2026/27 season.
READ ALSO:Asiama Reveals Bold Reforms Transforming Ghana’s Banking Sector