
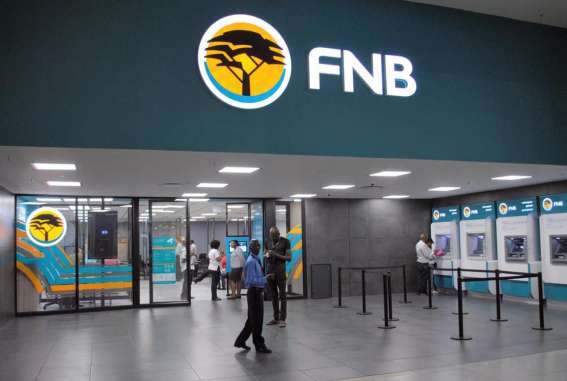
First National Bank Ghana has delivered a strong financial performance in the first nine months of 2026, with customer deposits surging nearly 29% and total assets climbing to GH¢7.32 billion, reinforcing its growing presence in Ghana’s competitive banking industry.
The bank’s unaudited financial results for the period ending September 2026 show that customer deposits increased by 28.95% to GH¢5.35 billion, while total assets expanded by 20.06% to GH¢7.32 billion.
Its loan book also recorded remarkable growth, with loans and advances rising by 54.55% to GH¢1.73 billion compared with the corresponding period in 2025.
The performance comes as the bank intensifies efforts to expand its customer base, strengthen lending activities and position itself as a major financial partner for individuals and businesses across Ghana.
Profit after tax reached GH¢48.82 million during the nine-month period, while profit before tax increased by 13.18% to GH¢77.53 million.
Chief Executive Officer of First National Bank, Sylvia Inkoom, believes the latest figures demonstrate that the bank’s distinctive approach to banking is producing meaningful results.
Deposits Cross GH¢5.35 Billion as Customer Confidence Grows
One of the strongest indicators of the bank’s performance is the substantial increase in customer deposits.
The 28.95% growth to GH¢5.35 billion represents a significant expansion in the funds entrusted to the bank by individuals, households and businesses.
Deposit mobilisation remains a critical measure of competitiveness in Ghana’s banking industry, where financial institutions continue to compete for customer savings, corporate accounts and business deposits.
The increase also provides First National Bank with a broader funding base to support its lending operations and other banking activities.
In a banking environment where customer confidence plays a major role in determining institutional growth, the latest figures suggest that First National Bank is strengthening its position in the market.
Sylvia Inkoom said the results reflected the progress being made under the bank’s growth strategy and the confidence customers continued to place in its operations.
“We have delivered steady profitability, grown deposits by nearly 29%, expanded lending by more than 54%, and continued to improve the quality of our loan book”.
Sylvia Inkoom
She added that the bank was building an institution capable of responding to changing customer expectations and the needs of Ghana’s economy.
Lending Explodes 54% as FNB Expands Its Market Presence
Beyond deposit mobilisation, First National Bank’s lending performance stands out as another major development in its financial results.
Loans and advances increased by 54.55% to GH¢1.73 billion, highlighting the bank’s expanding role in financing economic activities.
The growth comes at a time when access to affordable and reliable credit remains an important concern for businesses, particularly small and medium-sized enterprises that require financing to expand operations, purchase equipment and manage working capital.
Increased lending also presents opportunities for the bank to deepen relationships with customers and capture a larger share of Ghana’s credit market.
However, rapid loan expansion must be accompanied by disciplined credit assessment to prevent an increase in defaults and protect the quality of the bank’s assets.
First National Bank appears to be making progress on this front, with its non-performing loan ratio declining to 12.14% from 14.29% in September 2025.
Although the ratio remains an important area to monitor, the improvement suggests that the bank has made progress in managing its credit portfolio while expanding lending.
Fees and Trading Income Rescue Earnings
Another interesting feature of the bank’s performance is the growing contribution of non-interest income to its overall earnings.
Net fees and commission income increased by 47.14% to GH¢93.44 million, while net trading and other income rose by 18.48% to GH¢130.55 million.
These increases helped offset an 8.61% decline in net interest income, which fell to GH¢231.37 million.
The development highlights the importance of diversifying revenue sources as banks respond to changing interest rate conditions and evolving customer demands.
Overall operating income increased by 6.68% to GH¢455.36 million, while operating expenses grew by a comparatively modest 1.39% to GH¢367.65 million.
This relatively slower growth in operating expenses suggests that the bank maintained some control over its cost base despite expanding its operations.
Its cash and cash equivalents also increased by 45.01% to GH¢2.29 billion, while cash generated from operating activities reached GH¢266.09 million, reversing an outflow of GH¢216.11 million recorded during the same period in 2025.
Total equity increased by 11.48% to GH¢1.05 billion.
Meanwhile, the capital adequacy ratio declined from 37.55% to 24.07%, although the bank continued to report compliance with statutory liquidity requirements without related sanctions during the period.
Digital Banking and SME Financing Take Centre Stage
Looking ahead, First National Bank is placing technology, financial inclusion and customer relationships at the centre of its growth ambitions.
The bank intends to strengthen its Corporate and Investment Banking operations, expand its Retail and Commercial banking business and improve its digital banking services during the final quarter of 2026.
Sylvia Inkoom said the institution would continue investing in capabilities that support sustainable growth and improve the banking experience for customers.
“As we look ahead, our focus remains firmly on sustainable growth, digital innovation, financial inclusion and supporting businesses and individuals to achieve their ambitions”.
Sylvia Inkoom
She further explained the bank’s commitment to strengthening its technology infrastructure and customer relationships.
“We are investing in technology, strengthening our capabilities and deepening our customer relationships to ensure that First National Bank remains a trusted financial partner for generations to come.”
Sylvia Inkoom
The bank also plans to deepen its support for small and medium-sized enterprises, promote financial literacy, advance women’s economic empowerment and expand access to secure digital banking services.
These priorities could become increasingly important as Ghana’s financial services industry embraces digital innovation and seeks to extend banking access to underserved individuals and businesses.
With deposits now standing at GH¢5.35 billion, assets reaching GH¢7.32 billion and lending expanding by more than 54%, First National Bank has recorded a significant nine-month performance.
The challenge ahead will be sustaining this growth while protecting asset quality, maintaining adequate capital buffers and delivering consistent profitability.
Its ability to balance these priorities could determine how strongly the bank competes in Ghana’s increasingly dynamic banking industry.
READ ALSO: Expanding Cashew Exports Through Nadkansco Processing Ltd