

Banking in Africa is changing rapidly, with new technologies reshaping how people save, send money, receive salaries and access financial services without necessarily visiting a bank branch.
Across the continent, digital banking is challenging the traditional model of brick-and-mortar banking, bringing financial services closer to customers through smartphones and internet connectivity.
Angola’s ambitious move to establish its first digital banking platform, DUbank Angola, offers an interesting glimpse into this changing financial landscape. Backed by an initial investment of $12 million, the initiative sought to demonstrate that banking services could operate without the conventional dependence on physical branches, long queues and expensive banking infrastructure.
Although the project was announced ahead of its planned inauguration in 2020, its business model raises an important question about Ghana’s own financial future: Is the country doing enough to position itself at the forefront of Africa’s digital banking revolution?
With Ghana already boasting a growing mobile money ecosystem, expanding digital payment infrastructure and increasing smartphone adoption, the opportunity is significant. However, the next phase of financial innovation may require more than simply making traditional banking services available through mobile applications.
Banking Without Queues and Expensive Charges
One of DUbank’s most interesting propositions was its attempt to remove some of the inconveniences associated with conventional banking.
Customers would be able to access their accounts through a smartphone application and undertake transactions without necessarily visiting a banking hall.
Even cash deposits were incorporated into the model despite the absence of physical deposit facilities operated directly by the digital bank.
Explaining how the arrangement would work, Hirose said:Individuals just need to enter their smartphone application which will generate a payment guide. Customers should then go to any bank to make the deposit in their DUbank Angola account.
And, if your salary is domiciled in a DUbank Angola account, you can then perform any banking transaction without operating costs.
The platform was also expected to provide services covering salary accounts, payment slips, tax payments, insurance and money transfers.
Its multi-card arrangement, supported by the Interbank Service Company (EMIS), was intended to facilitate transactions while providing customers with greater flexibility.
Security was another important consideration. The platform was designed with separate passwords for account access and payments, while customers would receive transaction notifications and have the ability to block their accounts immediately when necessary.
These features demonstrate how digital banking can combine convenience with security when supported by appropriate technological and regulatory safeguards.
Ghana’s Mobile Money Success Is Not Enough
Ghana is not starting from zero in the digital finance revolution.
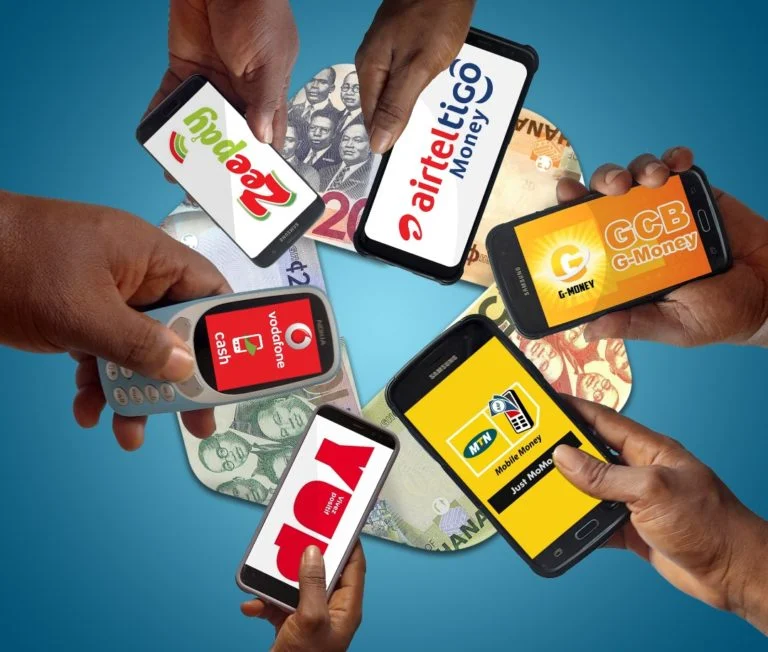
The country has established itself as one of Africa’s important mobile money markets, with millions of individuals and businesses increasingly relying on electronic transactions to make payments, transfer funds and manage their finances.
Mobile money has significantly changed financial behaviour, particularly among people who previously had limited access to conventional banking services.
However, the emergence of digital banking platforms introduces a different level of competition.
Mobile money services primarily provide payment and transfer capabilities, while a fully developed digital banking institution can potentially offer a broader range of financial products, including savings accounts, salary management, credit facilities, insurance and other banking services through a unified digital platform.
This distinction matters because Ghana’s financial sector must prepare for a future in which customers increasingly expect banking services to be accessible, affordable and available around the clock.
Traditional banks could face growing pressure to reconsider their operating structures, particularly where customers continue to encounter high transaction charges, lengthy processes and the inconvenience of visiting physical branches.
The competition may increasingly revolve around who can deliver the most convenient, secure and affordable financial experience.
The Regulatory Question Ghana Cannot Ignore
Angola’s experience also highlights an important issue for Ghana: technological innovation must move alongside effective financial regulation.
DUbank’s proposed operations raised questions about the regulatory framework governing digital banking platforms in Angola at the time. Despite the absence of specific regulations for such platforms, the company emphasised security and transparency, with the central bank expected to undertake audits.
Ghana must approach similar developments with a strong regulatory foundation.
The Bank of Ghana has an important responsibility to ensure that digital financial institutions operate within appropriate standards covering consumer protection, cybersecurity, data privacy, liquidity management and operational resilience.
The expansion of digital banking should not create opportunities for fraud, weak governance or the misuse of customer information.
Equally important is ensuring that regulatory requirements do not unnecessarily discourage innovative financial institutions from entering the market.
A balanced framework could encourage competition while protecting depositors and maintaining confidence in the financial system.
Ghana’s Next Banking Revolution Must Go Beyond Mobile Money
The future of African banking will increasingly be shaped by institutions capable of combining technology, affordability and financial inclusion.
Angola’s DUbank initiative presented an ambitious vision of banking without conventional branches, expensive account-opening requirements and unnecessary transaction costs.
Ghana has the technological foundations and financial market experience to explore similar opportunities.
However, achieving that ambition will require greater investment in financial technology, stronger digital infrastructure, regulatory flexibility and innovative partnerships between banks and technology companies.
The country must also address the digital divide, particularly among rural communities where internet access, smartphone ownership and digital literacy remain important considerations.
Ultimately, the next generation of banking competition will not simply be about how many branches a bank operates or how large its balance sheet becomes. It will increasingly be about how effectively financial institutions make banking accessible to ordinary people.
Africa’s banking future is moving towards digital platforms. Ghana has already made significant progress in electronic payments, but the bigger opportunity lies in transforming that foundation into a more comprehensive digital banking ecosystem.
READ ALSO: BoG Warns Ghana’s Economic Recovery and Inflation Gains Could Reverse in 2027