
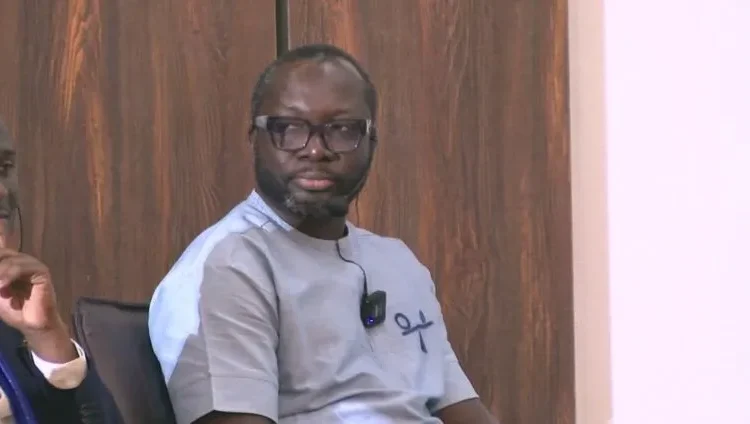
Ghana’s banking sector is pushing back against concerns that commercial banks are deliberately restricting access to credit, with the Ghana Association of Banks (GAB) insisting that lending conditions have improved significantly in recent months.
Chief Executive Officer of the Ghana Association of Banks, John Awuah, said the decline in commercial lending rates, coupled with strong growth in private sector credit, demonstrates that banks are responding to improving monetary conditions.
His comments come after the Bank of Ghana maintained the monetary policy rate at 14%, with the central bank seeking to assess the impact of global developments and domestic economic conditions on the financial sector.
Private Credit Growth Challenges Lending Concerns
According to Mr Awuah, evidence from the latest Monetary Policy Committee release points to stronger credit activity than public perception may suggest.
He cited a 29% year-on-year increase in private sector credit in real terms, arguing that the development contradicts claims that banks are unwilling to lend.
“Contrary to perhaps public view that banks are not lending, banks are interested in this or that, there is actually evidence on the ground to suggest that banks are lending.”
John Awuah
The increase in private sector credit comes at a time when the policy rate has remained unchanged since March. Mr Awuah said this stability has not prevented commercial banks from reducing their lending rates.
Lending Rates Continue to Fall
Mr Awuah explained that average bank lending rates have declined considerably despite the unchanged policy rate.
“Between March and September, the policy rate has been kept at 14 %. But I can tell you between March and September, bank lending rate has continued to decline from upwards of 18% somewhere in March to around where we are now, where we’re talking about 15.9.”
John Awuah
The distinction between average lending rates and rates applicable to new loans is particularly important.
Mr Awuah noted that the average lending rate of 15.9% still captures some legacy loans that were priced under previous market conditions. New borrowers, he said, are accessing considerably lower rates. “If you are taking real exposures on the books, new exposures, you are talking about between nine and 12 %,” he stated.
That gap highlights how monetary and financial conditions can influence borrowing costs even when the central bank leaves its benchmark rate unchanged.
Bad Loans Remain a Major Credit Barrier
Despite the improvement in lending rates, Mr Awuah warned that Ghana’s high non-performing loan ratio remains a significant challenge for banks.
He placed the sector’s NPL ratio at approximately 15.8%, considerably higher than levels he cited in some neighbouring and comparable African markets.
“The non-performing loan ratio in Togo is under 10 %. The non-performing loan in Côte d’Ivoire is under 7 %. The non-performing loan in Nigeria is under 9 %, and Ghana, we are clapping at 15.8%.”
John Awuah
He said the scale of loan defaults directly affects the amount of money banks can safely lend and the price at which they can lend it.
“For every 100 cedis of your money that we give out, we are likely going to lose 16 cedis. That is how, if you express it in cedis, it tells the story better.”
The cost of bad loans can ultimately be passed through the financial system as higher risk premiums, tighter lending conditions and more cautious credit decisions.
Loan Recovery Becomes Critical
Mr Awuah therefore argued that reducing lending rates cannot depend solely on monetary policy decisions. The ability of banks to recover funds when borrowers default is equally important.
He pointed to challenges surrounding the enforcement of collateral as one area requiring attention.
Under the Borrowers and Lenders Act, banks have mechanisms to initiate recovery when borrowers fail to meet their obligations. However, legal disputes can delay the process, leaving funds tied up for extended periods.
“What do we see? A bank uses the Borrowers and Lenders Act, notifies the collateral registry, notifies the court that this customer has met all the conditions for recovery and therefore the underlying asset is going to be disposed of. What do we see? They run to the court.”
John Awuah
According to him, prolonged recovery processes increase the risks associated with lending and restrict the ability of banks to recycle recovered funds into new loans. “Why it is important to do that is so that the next borrower does not suffer, so that the bank is enabled to be able to give funding to the next borrower,” he explained.
Banks Insist Lending Is Their Core Business
Mr Awuah also rejected suggestions that banks are inherently reluctant to provide credit to businesses and individuals.
He maintained that lending is fundamental to the existence of a banking institution and that banks would have every incentive to offer cheaper credit if the risks surrounding lending were reduced.
“Our job is to financially intermediate. The day we fail at that job, we don’t have banks, but we need the system to facilitate that. Tomorrow, a bank will pick up the phone and tell you, ‘Ellen, there’s a funding for you. We’ve looked at your credit history. We think you deserve one million Ghana cedis at 5 per cent.’ And then you come for it. That is why we exist. Banks do not shy away from lending because that is a piece of cake.”
John Awuah
His remarks place the debate over affordable credit beyond the policy rate alone. Lower borrowing costs will also depend on stronger credit risk management, faster loan recovery, effective collateral enforcement and a healthier business environment.
With private sector credit expanding and new lending rates falling to between 9% and 12%, the banking sector is showing signs of responding to improved monetary conditions. However, Ghana’s elevated NPL ratio remains a major hurdle.
Until banks can recover defaulted loans more efficiently and reduce the risks associated with lending, further reductions in borrowing costs could remain difficult to achieve. The ability to unlock cheaper credit may therefore depend as much on strengthening the credit ecosystem as it does on future monetary policy decisions.
READ ALSO: Aquaculture Chamber Engages 24Hr Authority on Industry Challenges