
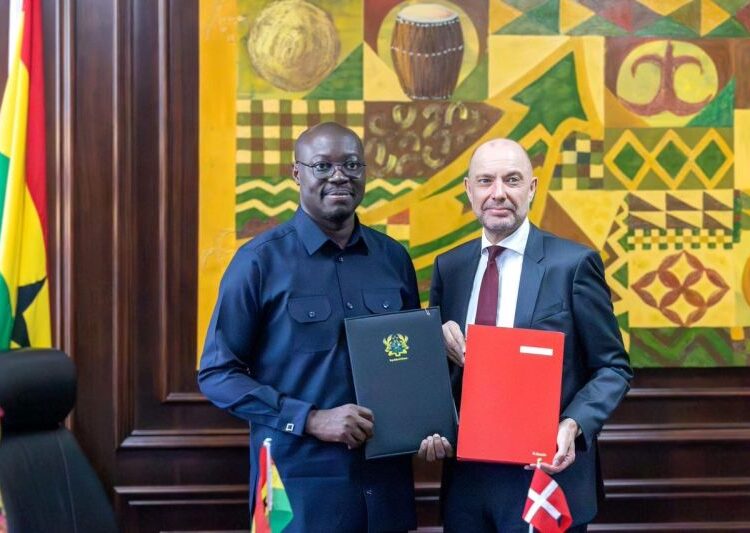
Ghana is moving closer to bringing one of the most difficult chapters in its economic history to a close, as the country makes significant progress in restructuring its external debt, with 16 out of 25 bilateral agreements with official creditors now finalised.
The latest assessment by the Global Sovereign Debt Roundtable (GSDR) signals that Ghana’s prolonged debt restructuring exercise is approaching its final stages, raising hopes that the country could soon complete a process that has weighed heavily on public finances, investor confidence and economic recovery.
According to the report, negotiations are continuing with Ghana’s remaining non-bonded commercial creditors. However, these creditors now account for less than 5% of the debt covered by the restructuring exercise, suggesting that the bulk of the outstanding negotiations has been substantially addressed.
The development represents a major milestone in Ghana’s efforts to restore debt sustainability after years of financial pressure, rising borrowing costs and difficult negotiations with international creditors.
While the remaining agreements still need to be concluded, the latest progress offers an encouraging indication that the country is gradually moving beyond the debt crisis that forced it to seek international financial assistance.
Ghana Moves Closer to Closing Its Debt Restructuring Chapter
The completion of 16 bilateral agreements out of the 25 arrangements with official creditors marks substantial progress in implementing Ghana’s debt treatment programme.
These agreements involve members of Ghana’s Official Creditor Committee (OCC), which was established to coordinate negotiations with bilateral lenders under the G20 Common Framework.
The remaining negotiations with non-bonded commercial creditors are now concentrated on a relatively small portion of the debt included in the restructuring exercise.
Although less than 5% may appear insignificant compared with the broader scale of Ghana’s debt obligations, concluding these outstanding arrangements remains important to achieving a comprehensive restructuring outcome.
The government must ensure that the remaining creditor claims are properly addressed to prevent unresolved obligations from becoming another source of uncertainty in the country’s external debt management.
The progress also places Ghana among countries that have made considerable advances in resolving sovereign debt difficulties through coordinated negotiations with official and private creditors.
How Ghana Slipped Into the Debt Nightmare
Ghana’s debt restructuring journey began in earnest in December 2022 when the government announced a suspension of payments on selected external debt obligations.
The decision covered Eurobonds, commercial loans and selected bilateral debts as authorities struggled to contain mounting fiscal pressures and restore confidence in the economy.
The suspension represented a dramatic turning point for a country that had previously maintained access to international capital markets and relied heavily on external borrowing to finance development expenditure and budgetary commitments.
The debt crisis also complicated Ghana’s relationship with international investors, particularly bondholders who faced uncertainty over the recovery of their investments.
As part of the broader economic recovery strategy, Ghana established its Official Creditor Committee on May 12, 2023, to coordinate bilateral debt restructuring negotiations under the G20 Common Framework.
The process subsequently became a critical requirement for securing financing assurances from international creditors and unlocking support from the International Monetary Fund.
Ghana eventually secured approval for a US 3 billion IMF programme, following the necessary assurances from creditors. The programme came with an initial disbursement of US 600 million, providing much-needed financial support as the country embarked on economic stabilisation and debt restructuring.
However, the IMF programme was never intended to resolve Ghana’s financial difficulties overnight. Restoring debt sustainability required difficult negotiations, fiscal adjustments and commitments to prevent another cycle of excessive borrowing.

Global Debt Negotiations Gather Momentum
Ghana’s progress is also part of a wider improvement in sovereign debt restructuring efforts involving several countries facing similar financial difficulties.
The GSDR report indicated that restructuring cases had continued to advance since April 2026, with Ethiopia, Ghana and Zambia making progress under the G20 Common Framework.
Sri Lanka and Suriname have also recorded advances in their respective restructuring processes outside the framework.
Apart from Ethiopia, where a bond exchange remained pending, the report noted that outstanding creditor negotiations across these cases involved only residual commercial creditors.
This suggests that several countries previously caught in prolonged restructuring negotiations are gradually approaching the implementation stage of their debt treatment arrangements.
The report further disclosed that 22 new bilateral agreements had been signed across the restructuring cases since April, highlighting growing momentum in efforts to resolve outstanding sovereign debt obligations.
The Paris Club website continues to track the implementation of bilateral agreements through periodic updates, providing a mechanism for monitoring progress after negotiations have been concluded.
The Final Hurdle Could Shape Ghana’s Economic Recovery
Despite the encouraging developments, completing the remaining negotiations will be important to ensuring that Ghana’s debt restructuring exercise achieves its intended objectives.
The outstanding commercial creditor claims may represent less than 5% of the debt covered by the exercise, but unresolved obligations can complicate the country’s efforts to establish a predictable external debt management framework.
Ghana must also demonstrate that the progress achieved through restructuring can translate into lasting improvements in public finances.
Debt restructuring provides breathing space by easing repayment pressures, but sustainable economic recovery ultimately depends on the government’s ability to manage expenditure, strengthen domestic revenue mobilisation and avoid excessive accumulation of new debt.
The completion of the remaining agreements could further improve Ghana’s standing among international creditors and strengthen confidence in its ability to honour future financial commitments.
It could also help reinforce the country’s broader economic recovery efforts as authorities seek to rebuild fiscal buffers, attract investment and restore access to sustainable financing.
After years of difficult negotiations and painful economic adjustments, Ghana is now approaching a significant turning point.
With 16 of the 25 bilateral agreements finalised and less than 5% of the covered debt still associated with remaining non-bonded commercial creditors, the country has moved considerably closer to completing its external debt restructuring.
The final agreements may be limited in size, but their successful conclusion could prove essential in closing one of the most consequential chapters in Ghana’s recent economic history.
READ ALSO: Security Consultant Urges Faster Drug Prosecutions and NACOC Resourcing