GEM Mining Consulting has revealed that the global clean energy transition is heading toward a severe supply deficit of key resources by 2035, warning that the primary threat stems from severe downstream refining bottlenecks and inaccurate mine forecasting rather than raw geological reserves.
According to a comprehensive market analysis released by the Santiago, Chile-based mining consultancy, projected mining projects will fulfill merely 68 percent of global lithium demand by 2035, alongside 74 percent for cobalt and 75 percent for copper.
While commodities like graphite and rare earths exhibit sufficient projected output on paper, they remain dangerously exposed to acute supply disruptions because their refining, chemical processing, and purification infrastructure are almost entirely concentrated within China.
“A reserve becomes strategically relevant only when it can be financed, permitted, extracted, processed, qualified and delivered through a resilient supply chain,” GEM said in its report.
GEM Mining Consulting
Expanding on these findings, the study asserts that traditional industry models dangerously overstate actual resource availability by simply measuring announced project pipelines against estimated consumer demand.
In practice, extraction projects regularly encounter prolonged permitting hurdles, high-cost financing hurdles, operational delays, metallurgical yield losses, and stringent end-user qualification protocols that together drastically reduce usable output.
To address this analytical gap, the Chilean consultancy introduced two evaluation metrics: a Volume Scarcity Index measuring gaps between extraction and primary demand, and a Supply Chain Fragility Index evaluating processing concentration, technological reliance, and geopolitical risks.
Under this framework, lithium ranks as the most supply-constrained mineral with a scarcity score of 80 out of 100, followed by cobalt at 65 and copper at 62, whereas rare earth magnets and battery-grade graphite suffer from severe fragility scores of 95 and 89 respectively despite positive physical extraction forecasts.
Evaluating Dual-Axis Mineral Scarcity
The consultancy’s findings indicate that the largest physical extraction shortfalls do not always represent an economy’s greatest strategic vulnerability.
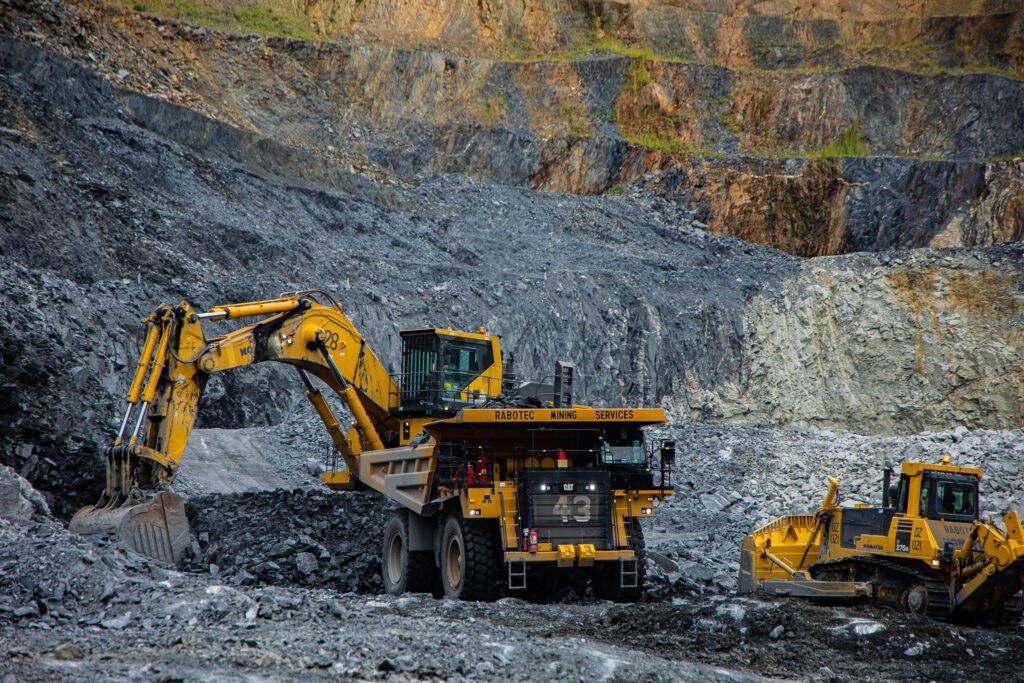
For base and battery metals like lithium, cobalt, and copper, industry stakeholders must prioritize bringing operational, highly dependable mining facilities online to plug structural deficits.
Conversely, securing graphite and rare earth supply chains demands an aggressive expansion of midstream refining capacity outside dominant market players.
Rare earth magnets clearly demonstrate this structural mismatch; GEM estimates that independent magnet processing operations beyond China will cover barely 15 percent of international demand by 2035, leaving global original equipment manufacturers structurally exposed regardless of total worldwide mining output.
Addressing the Need for Targeted Interventions
This research initiative was launched to overturn conventional, oversimplified policy assumptions that treat raw extraction capacity as a proxy for actual market supply.
By demonstrating that a hypothetical 100,000-tonne facility often delivers roughly 60,200 tonnes of commercial-grade output after accounting for real-world development friction, GEM highlights an urgent need for targeted public and private sector interventions.
Governments and institutional investors require a granular understanding of where supply chains fail, allowing them to allocate capital accurately.
Without targeted policy mechanisms tailored to specific mineral risks combining streamlined mine permitting for volume-deficient metals with massive midstream processing investments for geographically concentrated elements the global transition toward clean power technologies risks being stalled by preventable supply bottlenecks.
Strategic Solutions for Supply Chain Vulnerability
To navigate these dual challenges, industry analysts emphasize that national policy frameworks must differentiate between upstream extraction goals and downstream refining infrastructure.
For nickel, which scores 66 on the fragility scale due to heavy processing concentration in Indonesia and China, and cobalt, which registers a fragility score of 78, diversification of chemical conversion capacity is vital.
Meanwhile, copper demonstrates a relatively low fragility score of 36 despite its impending physical deficit, reinforcing that its main operational challenge lies in resource extraction rather than processing bottlenecks.
Ultimately, aligning financial, legal, and industrial resources toward both project execution and processing diversification remains the primary requirement for establishing long-term critical mineral security.
READ ALSO:Lalid Accused of Assaulting Artist After Cover Art Theft