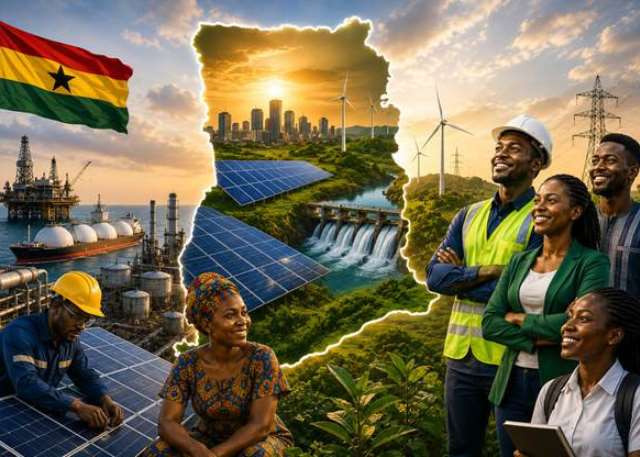
Ghana has called for a stronger shift from climate commitments to actual investment and implementation, arguing that Africa’s energy transition will remain constrained unless ambitious targets are converted into bankable projects, stronger infrastructure and financing that reflects the continent’s development realities.
The call places investment at the centre of Africa’s climate challenge. While countries across the continent continue to strengthen renewable-energy and climate commitments, the flow of capital into projects capable of delivering those ambitions remains inadequate.
For Ghana, the issue is particularly relevant to the energy sector, where the country is seeking to expand renewable generation, improve electricity access and reduce exposure to fuel-price and supply shocks without compromising the reliability required by households and industry.
The broader African picture shows the scale of the challenge. Africa has substantial renewable-energy potential, particularly in solar, yet continues to attract only a small share of global clean-energy investment.
At a regional energy meeting chaired by Ghana in 2025, the country highlighted that Africa accounted for about 17% of the world’s population but consumed only around 4% of global energy, while roughly 600 million people remained without electricity access.
That imbalance makes climate investment more than an environmental question. It is also an energy-access, industrialisation and economic-development issue.
From Climate Targets To Bankable Projects
The central challenge for African governments is increasingly moving beyond the formulation of climate targets.
Nationally Determined Contributions, renewable-energy targets and net-zero commitments provide policy direction, but they do not automatically create power plants, transmission lines, storage systems, clean-cooking infrastructure or climate-resilient industrial projects.
The investment gap emerges between the announcement of an ambition and the conditions required to finance it.
Ghana has previously argued that Africa must transform projects sitting in policy documents and development plans into ventures that investors can assess, finance and execute.
At the International Solar Alliance’s regional discussions, Ghana’s Energy Minister John Abdulai Jinapor stressed the need to move from ambition to action, including turning project pipelines into bankable investments and strengthening transmission infrastructure and technical capacity.
“Bridging the energy gap will require moving decisively from ambition into actions, transforming pipeline projects into bankable ventures, attracting private capital, and building the necessary transmission infrastructure and human resource capacity.”
John Abdulai Jinapor, Minister for Energy and Green Transition, Ghana.
The point is significant because the financing problem is not simply about the amount of money available globally.

It is about whether projects in African markets can provide investors with sufficient visibility over revenues, regulation, currency risk, offtake arrangements and long-term policy stability.
Without those conditions, even projects with strong development and climate benefits can struggle to reach financial close.
Ghana’s Energy Transition Faces The Same Financing Test
Ghana’s own transition illustrates why climate ambition has to be connected to wider energy-sector reform.
The country has been pursuing greater renewable-energy deployment while simultaneously relying on hydropower and thermal generation to maintain system reliability.
Solar and other renewable sources can reduce fuel exposure, but integrating more variable generation requires investment in transmission, storage and system management.
Ghana reported 200 megawatts of installed solar photovoltaic capacity at the end of 2024 and outlined plans for additional capacity, including a target of securing at least 10% of electricity generation from renewable sources, excluding hydropower, by 2030.
A five-year renewable-energy action plan valued at about US$3.4 billion was also outlined, targeting new capacity and development across the renewable-energy value chain.
Those ambitions demonstrate that the issue is no longer simply whether Ghana wants more renewable energy.
The harder question is how quickly the projects can be financed and connected to consumers.
Transmission is particularly important. Renewable resources and electricity demand are not always located in the same areas. Ghana’s strongest solar resources are concentrated in parts of the north, while major demand centres are further south.
Without adequate transmission infrastructure, additional generation capacity can fail to translate into additional usable electricity.
This makes grid investment inseparable from renewable-energy investment.
A solar project can be technically successful and commercially attractive, yet still deliver limited national value if the grid cannot evacuate its output reliably.
Private Capital Becomes Increasingly Important
Public financing alone cannot deliver the scale of investment required for Africa’s energy transition.
The continent’s governments face competing demands from healthcare, education, infrastructure, debt servicing and social protection.
Expanding climate and energy investment through public budgets therefore requires difficult fiscal choices.
That is why the private sector is becoming central to discussions about climate delivery.
But attracting private capital requires more than inviting investors into Africa.
Governments must create projects with credible revenue structures, predictable regulation and mechanisms that reduce risks that investors cannot reasonably absorb.
This includes guarantees, concessional finance, blended finance, local-currency instruments and project-preparation facilities.
The OECD and UNDP have similarly argued that climate plans become economically useful when they are designed to be ambitious, implementable and investable, with policies capable of mobilising private investment and connecting climate targets to wider development objectives.
For Ghana, this principle has implications beyond renewable generation.
It applies to electricity distribution, transmission expansion, battery storage, clean cooking, electric mobility and other infrastructure required for a broader energy transition.
Investment Must Address Energy Access And Reliability
Africa’s climate-finance debate can easily become focused on emissions reduction while overlooking the continent’s unfinished energy-access challenge.
For many African economies, the immediate priority remains obtaining enough reliable and affordable energy to support households, businesses and industrial development.
This creates a different transition equation from that faced by mature economies.
Africa needs to decarbonise while simultaneously expanding energy consumption.
That means climate investment should not be assessed only by the tonnes of carbon dioxide avoided.
It should also be measured by how much additional electricity is delivered, how many businesses receive reliable power, how much dependence on imported fuels is reduced and how effectively new infrastructure supports economic activity.
Ghana’s own policy direction reflects this balancing act. Its renewable-energy plans have been linked not only to climate objectives but also to energy security, access and economic development.
The country has also explored mini-grids, solar home systems and solar-powered infrastructure for communities where extending the conventional grid may be more expensive.
Regional Cooperation Can Lower Investment Barriers
Africa’s energy transition will also depend on infrastructure that crosses national borders.
Regional power trade offers an opportunity to improve reliability, optimise generation resources and make renewable investments more commercially viable.

A country with excess generation at one point in time could export electricity to a neighbouring market experiencing a deficit.
Larger regional electricity markets can also create stronger demand signals for investors than fragmented national systems.
However, that requires compatible regulations, reliable interconnections and payment systems capable of supporting cross-border transactions.
Ghana has already participated in regional energy cooperation and power trading through West African institutions.
Strengthening those arrangements could become increasingly important as renewable generation expands and electricity systems become more dependent on flexible balancing resources.
The same principle applies to financing.
Regional project pipelines could allow African institutions and investors to structure larger portfolios instead of approaching each renewable project as an isolated transaction.
Climate Finance Must Reflect African Risk
One of the persistent barriers to African climate investment is the cost of capital.
A project may be commercially viable in technical terms but become uneconomic once financing costs, currency risk and perceived sovereign risk are incorporated into its financial model.
This is particularly important for renewable projects because they require substantial upfront investment and typically depend on revenues generated over many years.
African governments have therefore continued to call for financing structures that recognise the continent’s development needs rather than applying risk assumptions that make projects prohibitively expensive.
At Ghana’s regional solar discussions, the country highlighted the disparity between Africa’s renewable potential and the small proportion of global clean-energy investment reaching the continent.
Ghana also pointed to the need for catalytic financing, blended-finance models and project preparation to accelerate deployment.
The African Development Bank has likewise highlighted the need to move from climate ambition towards implementation and investment, including stronger support for countries developing investment opportunities linked to their climate plans.
Ghana’s climate-financing needs have been estimated at billions of dollars for the implementation period of its climate commitments, with energy among the sectors requiring significant investment.
Delivery Will Define The Next Phase
The direction of Africa’s climate policy is increasingly clear.
The continent needs more renewable energy, stronger grids, improved access, greater energy efficiency and infrastructure capable of supporting climate resilience.
The challenge is execution.
Projects must move from announcements to procurement, from procurement to financing, and from financing to construction and operation.
That transition requires stronger coordination between energy ministries, finance ministries, regulators, development-finance institutions and private investors.
It also requires governments to address the underlying weaknesses that make investors cautious: weak utility finances, uncertain offtake arrangements, inadequate transmission capacity, currency risks and lengthy approval processes.
For Ghana, the opportunity is to ensure that climate policy becomes part of its broader economic and energy strategy rather than operating as a parallel agenda.
The country’s renewable-energy ambitions will have greater economic value if they reduce exposure to imported fuels, improve power reliability, create local industries and attract investment into Ghana’s energy infrastructure.

The wider African objective is similar.
Climate ambition has already produced targets. The next test is whether those targets can produce projects.
That means the credibility of Africa’s transition will increasingly be measured not by the number of commitments announced, but by the amount of capital mobilised, infrastructure delivered and energy made available to the people and businesses that need it.
For Ghana, turning that ambition into delivery could become one of the defining tests of its energy-transition strategy.