Tema Oil Refinery’s management says the Ministry of Finance plans to write off about US$120 million of debt owed to the government, a move that could materially reduce the refinery’s legacy liabilities while shifting attention to how the relief will be treated across the wider public sector.
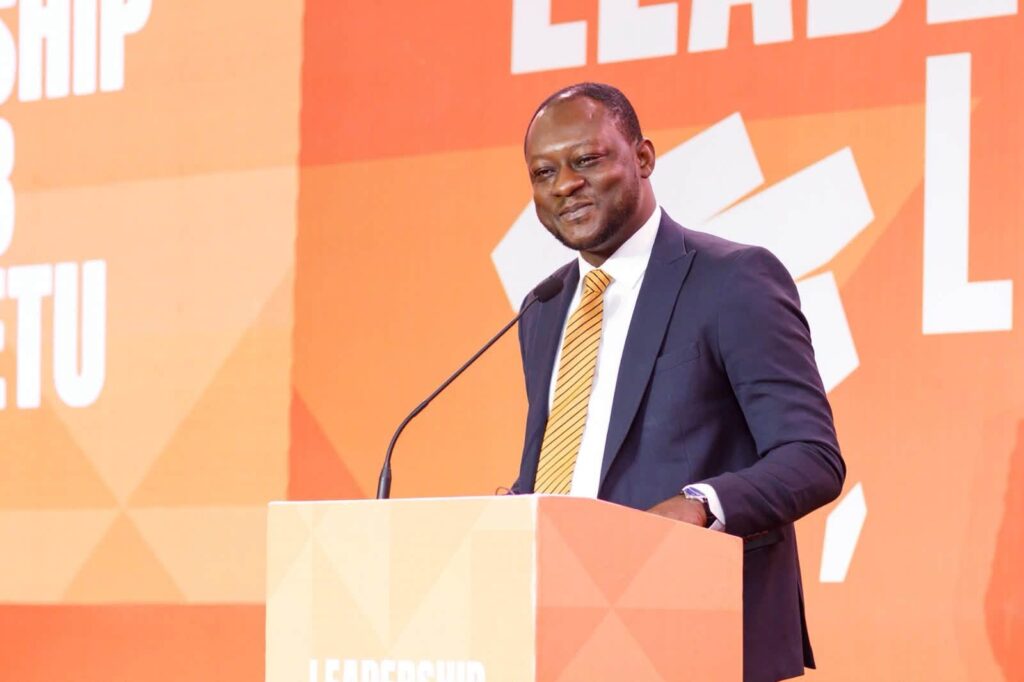
TOR Managing Director Edmond Kombat disclosed the plan during a working visit by Parliament’s Energy Committee, saying outstanding legacy obligations remain at roughly US$400 million after an earlier restructuring.
The disclosure comes at an important stage in TOR’s recovery. The refinery reported an after-tax profit of GH¢1.24 billion for 2025, its first positive financial result since 2016, yet management has repeatedly warned that old obligations can undermine the gains if they continue to sit on the balance sheet and accumulate financing costs.
The US$120 million figure should, however, be treated carefully. It is currently a plan described by TOR management rather than a completed write-off documented in a published Ministry of Finance statement, so the economic question is not only how much debt disappears from TOR’s books but where the corresponding cost is ultimately recognised.
Debt Relief Could Repair TOR’s Balance Sheet
For the refinery, reducing legacy debt could improve financial flexibility and make current operations easier to assess separately from liabilities accumulated during earlier periods of distress.
Large historical obligations can weaken a company’s ability to attract financing, negotiate with suppliers and direct cash towards maintenance, working capital and investment.
Mr Kombat described the scale of the proposed relief during the committee visit, saying the Ministry had indicated that part of the amount TOR owes the government would be written off. “It’s about $120 million. So if that is taken out, it will also further bring the debt down,” he said, while noting that the refinery still owes private and public-sector creditors.
The same disclosure identified Sahara and BP among private creditors, while GNPC and the Volta River Authority were named among state institutions to which TOR has obligations. Management is seeking discounts from some private creditors and wants Parliament’s Energy Committee to support efforts to resolve or net off selected public-sector balances.
Liability Does Not Vanish From the Public Sector
A write-off can improve TOR’s balance sheet without making the underlying economic cost disappear. When one state institution forgives a claim against another, the accounting treatment determines whether the burden is absorbed by central government, transferred elsewhere in the public sector or recognised through another fiscal mechanism.
That distinction matters because Ghana is trying to strengthen oversight of state-owned enterprise risks and contain contingent liabilities that can eventually reach the budget. Debt relief may be justified if it gives TOR a commercially viable balance sheet, but the public-finance case is stronger when the treatment is transparent and accompanied by reforms that reduce the likelihood of another accumulation of arrears.
The broader downstream context also matters because Ghana remains exposed to imported refined fuel and the foreign-exchange demand associated with those imports. A financially stronger TOR could support domestic refining resilience, but debt restructuring by itself cannot guarantee competitive output, reliable crude supply or lower pump prices.
Profitability Still Needs Operational Proof
TOR’s 2025 profit strengthens the recovery narrative, but the composition of that improvement is important. Ghana News Agency reported that management attributed the turnaround to favourable foreign-exchange movements, improved operational activity and continuing financial restructuring, which means the result should not be read as evidence that every structural weakness has already been resolved.
The refinery is simultaneously pursuing an ambitious expansion agenda. Its investment proposition includes higher refining capacity and a proposed 100,000-barrel-per-stream-day modular refinery, but new capacity will only create value if TOR can secure feedstock, working capital, reliable utilities, maintenance discipline and markets for its products.
That is why the debt decision should be assessed against future cash generation rather than headline relief alone. If restructuring allows TOR to operate consistently and finance more of its needs commercially, the write-off could support a stronger refinery; if old operating problems return, the state may simply have cleared space for liabilities to build again.
Budget Treatment Will Define the Fiscal Cost
The next step is confirmation from the Ministry of Finance and clarity on the accounting mechanism. The current US$120 million disclosure comes from TOR’s Managing Director, who said the Ministry intended to write off some debts owed to the government, but the Ministry has not yet publicly set out the precise budgetary treatment.

That confirmation will determine how the transaction should be interpreted by taxpayers, creditors and potential investors. A transparent restructuring could separate historical liabilities from TOR’s current operations and make it easier to judge whether the refinery can sustain profitability without repeated fiscal support.
Ghana’s objective should therefore be broader than producing a cleaner TOR balance sheet. The stronger outcome would be a refinery that converts debt relief into sustained throughput, stronger cash generation and a more reliable contribution to a downstream market that is still vulnerable to external fuel supply and pricing pressures.
READ ALSO: Oti, Savannah, Western North To Get 160-Bed Regional Referral Hospitals