
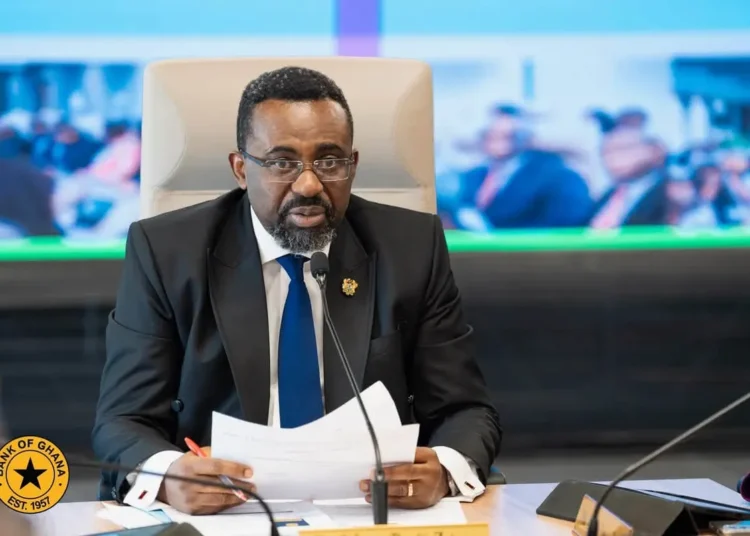
The Bank of Ghana (BoG) has issued a fresh challenge to the country’s banking sector, directing commercial banks to reduce their non-performing loan (NPL) ratios to 10% by the end of December 2026, as regulators intensify efforts to strengthen financial stability and improve the quality of bank lending.
The directive, announced by Governor Dr Johnson Pandit Asiama, places banks under renewed pressure to recover troubled loans, strengthen credit management and address weaknesses in their lending portfolios before the year ends.
Although Ghana’s banking sector has recorded improvements in capital adequacy and asset growth, the persistent level of non-performing loans remains a major concern for the central bank. The latest figures show that the industry’s NPL ratio stood at approximately 18.7% in August 2026, significantly above the prudential limit of 10%.
The gap presents a difficult assignment for banks, which must accelerate loan recovery efforts while protecting their balance sheets and maintaining the capacity to support businesses and households with credit.
BoG Sets December Deadline for Banks
Dr Asiama said the central bank expects financial institutions to make substantial progress in reducing their bad loans before the December deadline, stressing that banks must take responsibility for the quality of their lending portfolios.
“Let me use this opportunity to remind all banks of the requirement to reduce their NPL ratios to the prudential limit of 10% by the end of December,” he stated.
The directive signals a more demanding phase of regulatory supervision, with banks expected to move beyond reporting troubled loans and take concrete steps to recover outstanding debts, resolve distressed credit facilities and prevent additional loans from deteriorating.
The challenge is significant. Ghana’s banking sector recorded an NPL ratio of 20.7% in August 2025 before the figure declined to about 18.7% in August 2026.
While the reduction represents progress, the pace of improvement leaves banks with considerable work to do within the remaining months of the year.
Reaching the 10% target will require institutions to intensify engagement with borrowers, improve credit assessments and strengthen monitoring systems to identify repayment difficulties before they develop into serious defaults.
From Loan Provisions to Aggressive Recovery
The Governor’s remarks also point to a shift in the central bank’s approach to managing bad loans. Rather than allowing banks to rely primarily on provisions to absorb potential losses, regulators want institutions to tackle the underlying problems contributing to loan defaults.
Dr Asiama explained that the industry must embrace a more active approach to credit risk management.
“The increasing regulatory attention to NPLs therefore represents a shift from simply provisioning for problem loans to ensuring that banks actively prevent, manage, recover, and resolve problem loans.”
Dr Johnson Pandit Asiama
The distinction is important for banks because provisioning for bad loans does not necessarily recover the money owed by borrowers. Although provisions help institutions recognise potential losses and protect their financial statements, actual recovery remains essential to restoring the funds tied up in distressed credit facilities.
A stronger recovery culture could help banks improve asset quality, release resources for productive lending and reduce the financial pressure associated with loans that remain unpaid for extended periods.
Banks will also need to examine the reasons behind defaults, including borrowers’ repayment capacity, weaknesses in credit appraisal and changes in the economic conditions affecting businesses.
The effectiveness of these measures will determine whether the sector can achieve the central bank’s target without creating additional pressure on borrowers who are facing genuine financial difficulties.
Banking Assets Surge to GH¢500.2 Billion
The directive comes at a time when Ghana’s banking sector is expanding, with total assets rising by 20.4% to GH¢500.2 billion in August 2026 from GH¢415 billion recorded a year earlier.
The growth reflects an increase in the overall size of the banking industry, but it also raises the importance of ensuring that expanding balance sheets are supported by sound lending decisions and effective risk management.
Rapid asset growth alone does not guarantee that banks are becoming more resilient. The quality of the loans they extend, their ability to recover debts and the strength of their capital buffers remain essential indicators of financial health.
The central bank’s focus on non-performing loans therefore places asset quality at the centre of its efforts to consolidate the sector’s recovery.
If banks fail to manage credit risks effectively, rising loan defaults could weaken earnings, increase provisioning expenses and constrain their ability to extend fresh credit to businesses and households.
Stronger Capital, but Risks Remain
Ghana’s banks have also recorded improvements in capital adequacy, with the sector’s capital adequacy ratio increasing from 18.3% to 19.1%. The ratio remains comfortably above the regulatory minimum of 13%.
Dr Asiama disclosed that all 23 banks operating in the country had met the applicable regulatory capital requirements, marking an important development for a sector that has faced significant balance-sheet pressures in recent years.
However, the Governor cautioned that restoring capital is only the beginning of the process of building a stronger banking industry.
Banks must maintain capital levels that reflect their individual risk profiles and establish adequate buffers to withstand future economic and financial shocks.
The distinction between meeting minimum capital requirements and maintaining healthy loan portfolios is particularly important. A well-capitalised bank can still experience pressure if a significant proportion of its borrowers fail to repay their loans.
Consequently, the central bank’s latest directive places renewed emphasis on ensuring that capital strength is matched by disciplined lending, effective recovery procedures and stronger internal controls.
Banks Face a Race Against Time
With the end of December approaching, banks have limited time to narrow the gap between the current NPL ratio of approximately 18.7% and the required 10% threshold.
The scale of the adjustment means financial institutions will need to review their existing problem loans, strengthen recovery strategies and prevent new credit facilities from slipping into default.
The outcome will have implications beyond individual banks. Healthier loan portfolios can strengthen confidence in the financial system and improve banks’ capacity to channel deposits into productive economic activities.
However, the speed of recovery will depend partly on borrowers’ financial conditions, the effectiveness of loan restructuring where appropriate and banks’ ability to enforce repayment obligations.
READ ALSO: Cedi’s Brief Recovery Masks Growing Dollar Supply Crisis