
The Bank of Ghana (BoG) has raised fresh concerns over the growing adoption of foreign-currency stablecoins, warning that their increasing use could threaten the country’s monetary sovereignty, weaken the Ghana cedi and undermine the central bank’s ability to control monetary policy.
The warning signals a growing regulatory concern as digital assets become increasingly embedded in global financial transactions, creating new challenges for countries seeking to protect their domestic currencies and maintain control over their financial systems.
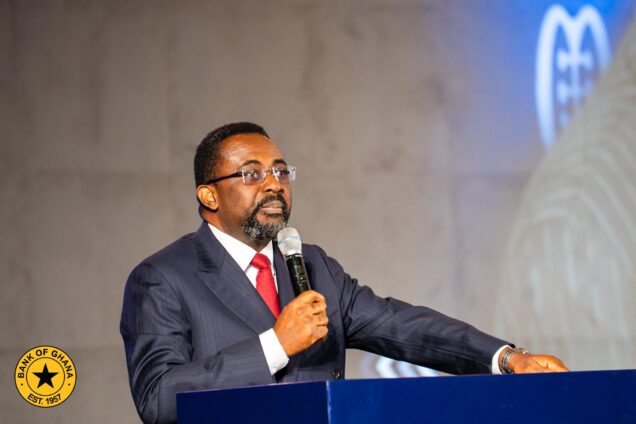
Governor of the Bank of Ghana, Dr Johnson Pandit Asiama, said the expanding use of stablecoins, particularly those denominated in foreign currencies, could encourage currency substitution, disrupt capital flows and introduce additional risks to financial stability.
His remarks highlight the difficult balance facing Ghana as it seeks to benefit from financial technology innovations without allowing the growing influence of foreign digital currencies to weaken the position of the cedi.
Speaking at the Africa Virtual Assets Summit 2026, Dr Asiama acknowledged that stablecoins could improve payment systems and settlement processes but warned that their wider adoption could have consequences beyond the convenience they offer users.
“Stablecoins may offer benefits for payments and settlement, but their growing adoption, particularly those denominated in foreign currencies, could have implications for monetary sovereignty, currency substitution, capital flows, and the effectiveness of monetary policy.”
Dr Johnson Pandit Asiama
Foreign Stablecoins Could Challenge the Cedi
The growing popularity of stablecoins presents a potentially complicated challenge for Ghana’s monetary authorities.
Stablecoins are digital assets designed to maintain a relatively stable value by being linked to traditional currencies or other assets. Those backed by major foreign currencies, particularly the US dollar, can provide users with an alternative means of storing and transferring value without relying entirely on conventional banking channels.
While this can make cross-border payments and digital transactions more convenient, the implications for countries such as Ghana could be significant if foreign-currency stablecoins become widely used for everyday economic activities.
A sustained shift towards dollar-denominated digital assets could gradually reduce demand for the Ghana cedi, particularly if individuals and businesses increasingly prefer holding their savings and conducting transactions in foreign-currency stablecoins.
Such a development could complicate the Bank of Ghana’s efforts to influence domestic monetary conditions.
The central bank relies on monetary policy instruments to manage inflation, influence interest rates and support the stability of the domestic currency. However, widespread adoption of foreign-currency digital assets could weaken the transmission of these policy measures if a growing share of economic transactions takes place outside the cedi-based financial system.
This raises concerns about how effectively the BoG could influence liquidity conditions and manage currency demand in an increasingly digital financial environment.
BoG Moves to Introduce Stablecoin Regulations
Against this backdrop, Dr Asiama disclosed that the Bank of Ghana is developing a stablecoin directive to provide regulatory guidance for activities within the sector.
The proposed directive is expected to form part of broader efforts to ensure that digital financial innovations operate within a framework that protects consumers, strengthens financial oversight and safeguards monetary stability.
The BoG is also collaborating with the Securities and Exchange Commission (SEC) and the Financial Intelligence Centre (FIC) to develop regulatory instruments and supervisory arrangements for virtual assets.
The cooperation reflects the recognition that digital asset activities cut across several areas of the financial system, making coordination between regulatory institutions increasingly important.
Without appropriate supervision, the rapid expansion of virtual assets could create gaps in financial oversight, particularly where transactions involve foreign currencies, cross-border transfers and activities outside traditional banking structures.
The planned stablecoin directive therefore represents an important part of Ghana’s attempt to establish clear regulatory boundaries while allowing responsible innovation to take place.
Virtual Asset Law Opens New Regulatory Chapter
Ghana has already taken a significant legislative step towards regulating the growing virtual asset industry through the passage of the Virtual Asset Service Providers Act, 2025 (Act 1154).
Dr Asiama described the legislation as a major milestone in the country’s efforts to establish a regulatory framework for virtual assets.
The law provides an important foundation for bringing virtual asset service providers within a formal regulatory structure, strengthening oversight of activities that have increasingly attracted attention from financial authorities.
However, the passage of the legislation also places additional responsibility on regulators to develop effective supervisory arrangements capable of responding to the speed and complexity of digital financial innovation.
The challenge extends beyond registering operators and monitoring transactions. Regulators must also consider how emerging digital assets interact with monetary policy, exchange rate management, capital movements and the stability of the broader financial system.
Ghana Faces a Delicate Digital Finance Balancing Act
The concerns raised by the BoG come at a time when digital finance is creating new opportunities for individuals and businesses to access faster and potentially more efficient payment services.
Stablecoins could improve the efficiency of international settlements, reduce certain transaction costs and provide alternative payment channels. These benefits could be particularly relevant to businesses involved in international trade and individuals who regularly send or receive money across borders.
However, the growing attraction of foreign-currency stablecoins could introduce a new dimension to Ghana’s longstanding efforts to strengthen confidence in the cedi.
If households and businesses increasingly turn to dollar-backed digital assets as stores of value, the implications could extend to foreign exchange demand, domestic liquidity and the effectiveness of monetary policy.
The Bank of Ghana must therefore ensure that the benefits of digital finance do not come at the expense of the country’s ability to manage its own monetary system.
Dr Asiama’s warning suggests that the central bank intends to pay closer attention to these developments as virtual assets become more prominent in Ghana’s financial sector.
The coming regulatory measures will be crucial in determining how the country accommodates digital financial innovation while protecting the cedi, maintaining financial stability and preserving the effectiveness of its monetary policy framework.
Ghana’s digital finance ambitions are expanding, but the BoG is making it increasingly clear that innovation must operate within safeguards that protect the foundations of the country’s financial system.