
The Government’s efforts to strengthen domestic revenue mobilisation in 2027 will hinge partly on expanding AI-driven tax administration, improving electronic invoicing and revising statutory fees, as it seeks to increase revenue without introducing new taxes.
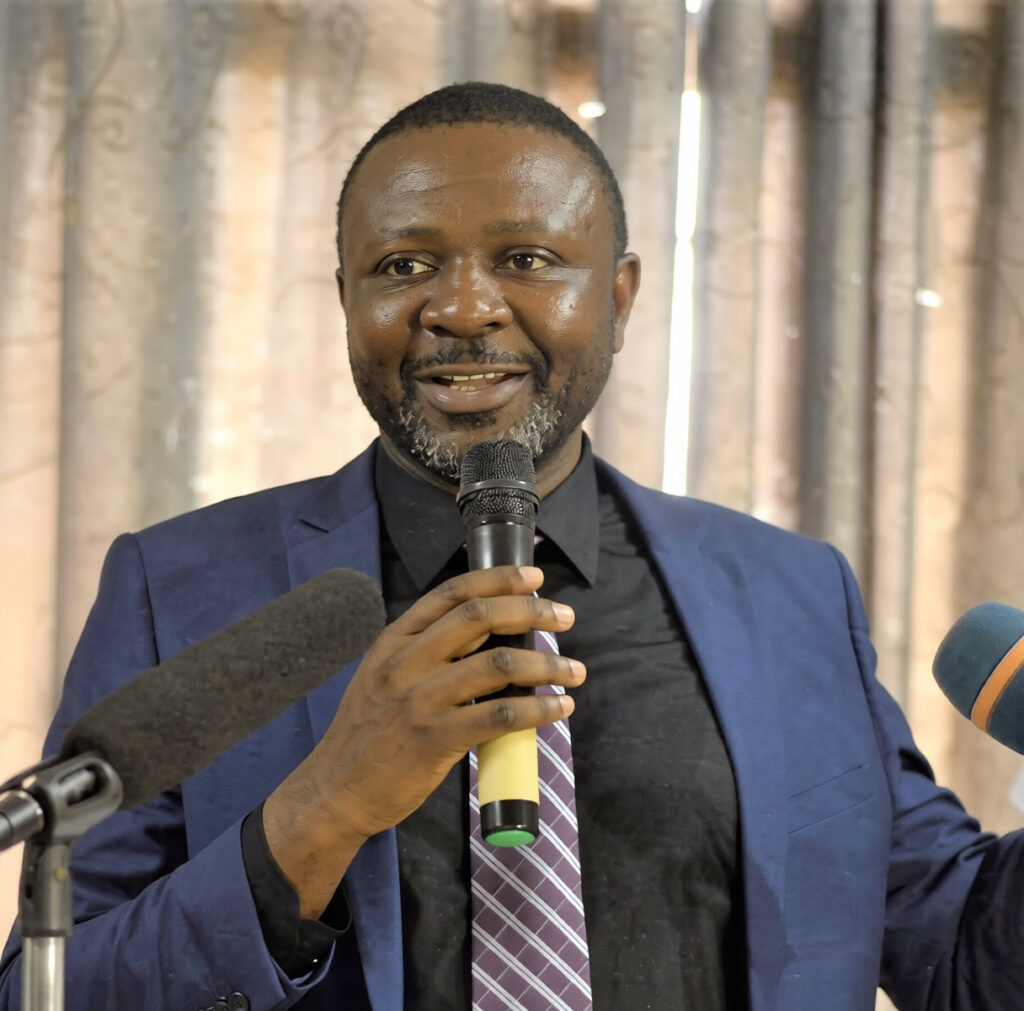
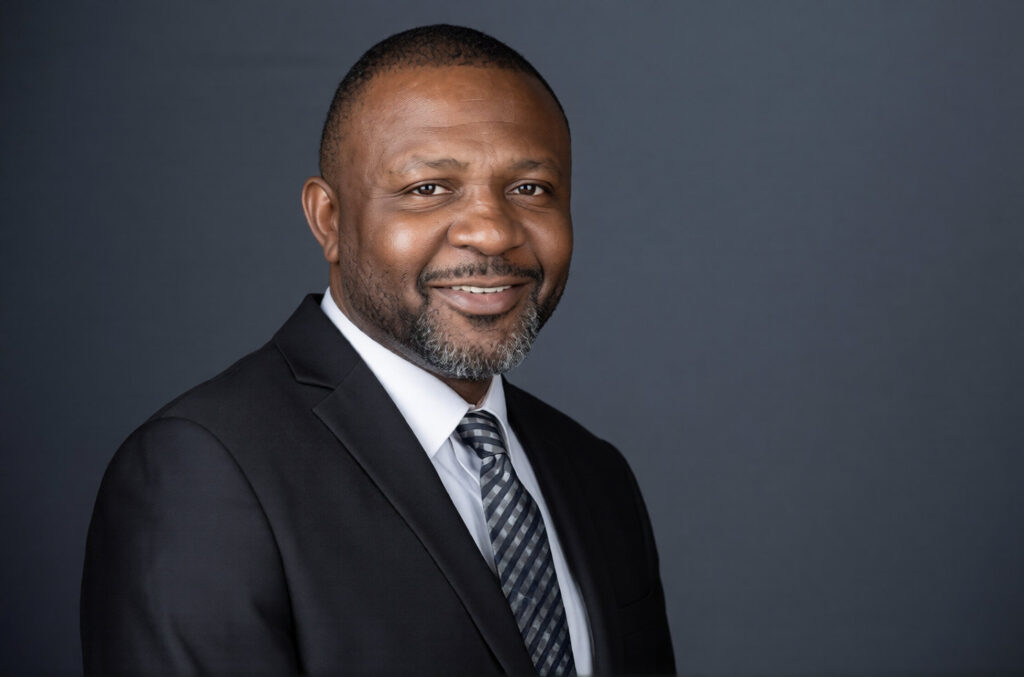
Professor of Finance at Andrews University, Professor Williams Kwasi Peprah has identified technology-enabled revenue collection as a significant component of the Government’s fiscal approach.
Speaking in an exclusive interview with The Vaultz News Network on the 2027 Budget, he also highlighted “electronic invoicing and digital taxation as mechanisms for strengthening compliance” while drawing attention to the revenue implications of the proposed review of the Fees and Charges Act.
“The good thing is that in 2026, we’ve seen that the Government is using the Publican AI system to collect revenue at the port. This has been very useful. Government must make sure that the strategy is applied to not only the sea ports, but also the landed ports.”
Williams Kwasi Peprah, PhD
He accentuates the necessity of commensurating the initiative’s geographical coverage with the magnitude of commercial exchanges between Ghana and neighbouring countries, particularly within the Economic Community of West African States (ECOWAS).
In his view, the proposed expansion would enable the revenue authority to “capture additional revenue from cross-border commercial activities that may not be adequately accounted for under existing collection arrangements.”
Beyond border operations, the Finance Academic identified “electronic invoicing” as another administrative intervention capable of strengthening tax compliance. He proposed transitioning from “conventional VAT invoices to electronic invoicing systems” to improve transaction monitoring and reinforce the collection of Pay As You Earn (PAYE) income tax and Value Added Tax (VAT).
The adoption of such systems would be a broader deployment of information technology infrastructure in 2027, through which the Government intends to undertake major public financial management and legislative reforms.
Focusing on income generated through digital platforms, particularly social media, Professor Peprah identified the implementation of digital taxation as an additional mechanism for bringing revenue earned from online activities within the existing tax collection framework.
Fees and Charges Act Could Provide Alternative Revenue Stream
On Thursday, November 12, 2026, the the Finance Minister, Dr Cassiel Ato Forson announced the Government’s intention to modernise key tax laws, address revenue leakages and improve taxpayer services, while affirming that “in this 2027 budget, we will not introduce any new tax.”
However, this commitment does not preclude the Government from pursuing alternative revenue measures. Professor Peprah draws attention to the proposed revision of the Fees and Charges Act, which could enable the state to generate additional revenue through adjustments to statutory charges, despite its decision not to introduce new taxes.
Although the Government has pledged not to introduce new taxes or increase existing tax rates, the Finance Academic cautioned that the proposed legislative review could create “additional financial obligations for individuals and businesses accessing public services.”
He explained that the distinction between taxation and statutory charges is important in evaluating the Government’s revenue commitments, as “fees are also revenue generation items for the Government.”
The proposed review, he indicated, could allow the Government to mobilise additional revenue through adjustments to charges imposed on public services, even as it maintains its commitment to the existing tax framework.
Professor Peprah consequently cautioned that Ghanaians who rely on services attracting statutory fees should anticipate possible increases if the amendments result in higher charges.
Accountability in Four-Year Investment Agenda
Beyond the revenue measures outlined in the 2027 Budget, Professor Peprah emphasised the need for institutional accountability and policy continuity in implementing the Government’s proposed US$10 billion investment.
“The good thing about this plan is that it is not a one-time expenditure; it is spread over four years. This means that the 2027 and 2028 budgets will be prepared in line with the US$10 billion agenda, particularly in terms of capital expenditure (CAPEX), which involves investment in projects that propel the economy.”
Williams Kwasi Peprah, PhD
While describing the phased implementation as “a positive feature” of the initiative, he stressed that its success would depend on ensuring that “procurement processes are fair and not so expensive, the implementation of these projects should be followed well, and should be managed in such a way that all projects within this period will be completed within time to make sure that it is fulfilled.”
He expressed concern that electoral considerations could disrupt the implementation of the four-year agenda, particularly as the country approaches another election cycle. He therefore underscored the importance of preserving long-term development objectives across successive administrations.
Professor Peprah further posits that the KPIs would provide Ghanaians with measurable benchmarks for assessing the Government’s delivery of the proposed investment commitments, insisting that “this should not just be a talk show.”
READ ALSO: Korle Bu Performs Ghana’s First Minimally Invasive Heart Valve Replacement