
Petra Master Trust has reported investment returns of up to 15.63% across its pension schemes, outperforming inflation and strengthening efforts to protect contributors’ retirement savings against rising living costs.
The performance highlights the investment gains recorded by the company’s pension products, with the Petra Opportunity Pension Scheme emerging as the strongest performer, followed closely by the Petra Advantage Pension Scheme. The results also show that contributors earned positive real returns, meaning their investments grew faster than the inflation rate cited at the company’s annual meeting.
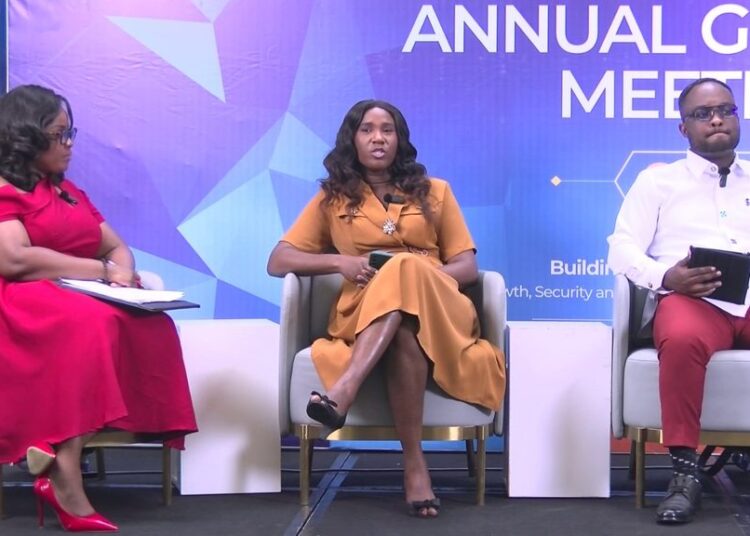
Speaking at the Petra Master Trust Scheme Annual General Meeting, Head of Portfolio Management and Operations, Yvonne Buliga, disclosed that the Opportunity Pension Scheme returned 15.63%, while the Advantage Pension Scheme recorded 15.27%.
The Savings Booster Scheme also delivered a positive return of 11.73%, exceeding the inflation rate of approximately 5.4% cited at the event.
“I’m happy to report that they all generated positive real returns,” Ms Buliga said, highlighting the schemes’ ability to grow contributors’ funds while protecting their purchasing power.
The results offer encouraging news for pension contributors seeking to build financial security during retirement, particularly as workers face the challenge of balancing present expenses with the need to save for the future.
Petra Pension Schemes Outperform Inflation
The performance of Petra’s pension schemes stands out because investment returns that exceed inflation help preserve the real value of contributors’ savings.
When inflation rises, the purchasing power of money declines, meaning retirees may need more funds to maintain the same standard of living. Pension investments that deliver returns above inflation can help contributors protect their accumulated wealth and improve their financial position over time.
With the inflation rate cited at the meeting standing at approximately 5.4%, all three schemes delivered returns above that level.
The Opportunity Pension Scheme recorded the highest return of 15.63%, followed by the Advantage Pension Scheme at 15.27%. The Savings Booster Scheme posted 11.73%.
Although investment performance can change from one period to another, the reported figures indicate that Petra’s schemes delivered positive real returns during the period under review.
The performance also places renewed attention on the importance of investment management in the pensions industry, where the ability to grow funds while managing risk remains essential to contributors’ long-term financial wellbeing.
Advantage Scheme Nears GH¢4 Billion in Assets
Beyond the returns, Petra’s pension schemes have recorded substantial growth in the value of funds under management.
The Petra Advantage Pension Scheme added approximately GH¢800 million in growth, bringing its net asset value to just under GH¢4 billion.
The Petra Opportunity Pension Scheme also recorded growth of about GH¢544 million, increasing its net asset value to GH¢2.64 billion.
These figures highlight the growing pool of retirement savings entrusted to the company and the importance of responsible investment decisions in managing contributors’ money.
The increase in asset values also reinforces the need for pension fund managers to maintain strong oversight, communicate investment performance effectively and ensure that members understand how their savings are being managed.
As pension assets expand, contributors have a greater interest in knowing where their money is invested, how their portfolios are performing and what those results mean for their retirement plans.
Petra Emphasises Transparency in Pension Management
While investment returns remain important, Petra says transparency is central to maintaining confidence in the management of contributors’ funds.
Ms Buliga explained that members could access information about daily investment returns and asset allocation through the company’s online portal.
The platform provides contributors with an avenue to monitor their investments and obtain information about how their pension funds are performing.
“Transparency is very key for all of us here at Petra, because at the end of the day, the money is not for us. It’s for all of our scheme members.”
Yvonne Buliga
The emphasis on transparency comes as pension contributors increasingly seek better access to information about their retirement savings.
Regular access to investment information can help members understand the progress of their funds and make more informed decisions about their financial futures.
It also places responsibility on pension managers to communicate clearly about investment outcomes and maintain accountability to the workers whose contributions they manage.
Petra Warns Workers Against Relying Solely on Mandatory Pensions
Despite the positive investment results, Petra is urging workers to take a more active role in planning for retirement instead of relying exclusively on mandatory pension contributions.
Head of Retail Business at Petra, Seth Koomson, cautioned that compulsory pension arrangements should not automatically be viewed as sufficient to guarantee a comfortable retirement.
“Most times, when something is mandatory, it is the bare minimum required,” he said.
His remarks draw attention to the financial decisions workers make during their active years and how those choices can influence their living standards after leaving employment.
Although statutory and occupational pension contributions provide an important foundation for retirement income, additional savings and investments can help workers prepare for expenses that may exceed their expected pension benefits.
Petra is therefore encouraging members to consider opportunities that complement their existing pension arrangements.
These include additional investment options, homeownership opportunities and free financial consultations designed to help members identify gaps in their financial plans.
The consultations are intended to help workers assess their financial positions and consider practical steps towards achieving their long-term goals.
Nearly 80 Members Secure Homes Through Petra
Petra’s efforts to broaden its support for members extend beyond traditional pension investment products.
Mr Koomson disclosed that the company had helped nearly 80 scheme members secure homes over the past two years, highlighting homeownership as one of the opportunities available to workers seeking greater financial stability.
The initiative reflects a broader approach to financial planning in which retirement preparation involves more than accumulating pension contributions.
Homeownership, additional investments and disciplined saving can form part of a worker’s long-term financial strategy, although individual decisions must account for affordability, income stability and other financial commitments.
Mr Koomson urged workers to take deliberate steps towards securing their financial futures rather than placing the entire responsibility on employers or existing pension arrangements.
“We want workers to own their future. Don’t leave it to your employer, and don’t leave it to your tier 2, tier 3, and your tier 1 with SSNIT. There are intentional steps you have to take.”
Mr Koomson
His comments reinforce the importance of personal financial responsibility alongside the role played by employers, pension trustees and the Social Security and National Insurance Trust in supporting retirement security.
Retirement Planning Takes Centre Stage
Petra’s latest performance figures provide a positive update for contributors, with all three schemes recording returns above the inflation rate cited at the annual meeting.
However, the company’s appeal to workers highlights a wider challenge: strong pension investment performance alone may not eliminate every financial concern associated with retirement.
Workers must also consider their expected expenses, savings habits, housing needs and potential sources of income after leaving active employment.
Petra’s combination of pension investment management, online performance reporting, financial consultations and homeownership opportunities is intended to support members in addressing these needs.
Ultimately, building a comfortable retirement requires a long-term commitment to saving, informed investment decisions and regular reviews of personal financial goals.
The reported returns offer encouragement to Petra’s contributors, while the company’s call for additional financial planning serves as a reminder that preparing for retirement begins well before the final years of employment.
READ ALSO: Fitch Predicts Strong Vehicle Assembly Growth for Ghana