Republic Bank (Ghana) PLC is setting its sights on a larger share of Ghana’s mortgage market, targeting between 40% and 42% by the end of 2026 as it seeks to strengthen its position in housing finance.
The bank currently controls more than 38% of the mortgage market, according to Managing Director Dr Benjamin Dzoboku. He said the institution is determined to build on that position by placing mortgage financing back at the centre of its growth strategy.
The target represents a renewed push into a segment that has been closely associated with Republic Bank since its establishment. Rather than treating mortgages as one product among many in its commercial banking operations, the bank is now seeking to reconnect with the business that formed the foundation of its operations.
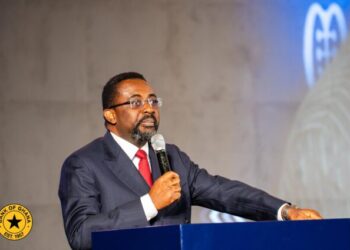
“That is our dream, and that is the reason why the bank was set up initially as a mortgage finance, and then we evolved to become a commercial bank. So, when I took over, I decided that ‘let’s go back to the reason why the company was set up for’. We have over 38% market share. And it is my expectation that by the end of the year we should be about 40 to 42.”
Dr Benjamin Dzoboku
Mortgage Banking Returns to Centre Stage
Republic Bank’s renewed focus comes as demand for housing finance remains a major issue in Ghana, where the cost and accessibility of mortgages can determine whether many prospective homeowners are able to purchase or complete properties.
The bank has therefore been working on ways to make its mortgage operations more responsive to customers. In January 2026, it announced plans to reconfigure its mortgage financing operations, with digital verification, shorter processing times and specialised advisory services forming part of the strategy.
These measures point to a broader attempt to make the mortgage journey less cumbersome for customers.
The bank is also positioning its mortgage offering to serve different categories of borrowers rather than relying on a single home loan product. Its portfolio includes home purchase, home equity, home completion, home improvement, buy-build-and-own, pension-backed, executive, switch and land mortgages.
Such variety gives the bank room to target customers at different stages of the property ownership cycle, from people buying their first homes to existing homeowners seeking financing for improvements or refinancing.
Pricing Could Shape Mortgage Expansion
Mortgage pricing will remain an important factor as Republic Bank seeks to translate its market position into further growth.
The bank’s published mortgage information indicates that its individual cedi mortgage rate is currently 18% per annum fixed, while its published USD mortgage rate is 11.5% per annum.
Cedi mortgages can run for as long as 20 years, while USD mortgages can extend up to 15 years.
The difference between the two currency options reflects the range of financing needs within the bank’s customer base. At the same time, the cost of borrowing remains a critical consideration for households assessing whether monthly mortgage payments fit comfortably within their incomes.
Republic Bank’s strategy therefore places its products, pricing and customer experience under the spotlight as it seeks to add another two to four percentage points to its existing market share.

National Mortgage Scheme Adds Momentum
The bank’s mortgage ambitions are also being supported by its involvement in broader efforts to expand access to affordable housing finance.
Republic Bank has participated in the National Mortgage Scheme, which is aimed at improving access to lower-cost mortgage financing for eligible homeowners.
In August 2026, the National Homeownership Fund announced the resumption of lending under the scheme at an interest rate of 8.4%, following a review undertaken in collaboration with Republic Bank.
The lower rate creates another avenue through which eligible borrowers can access housing finance, while strengthening the bank’s role in the mortgage market.
Such initiatives could become increasingly important as Republic Bank attempts to push its market share beyond 38% before the close of the year.
Pension Savings Open Another Door
Republic Bank is also widening its mortgage reach through pension-backed financing.
The product allows eligible pension contributors to leverage qualifying retirement savings towards homeownership. The initiative builds on the bank’s earlier partnership with corporate trustee Petra Trust.
This approach gives potential homeowners another route into the property market, particularly those who may have accumulated pension savings but face difficulties raising traditional upfront financing.
By connecting mortgage financing with pension contributions, Republic Bank is attempting to expand the pool of customers who can potentially qualify for homeownership.
Race to 42% Enters Final Stretch
With the end of 2026 approaching, Republic Bank’s target of 40% to 42% will put its mortgage strategy under greater scrutiny.
Moving from more than 38% to the targeted range will require the bank to maintain customer acquisition, improve processing efficiency and sustain its focus on housing finance.
The ambition also signals a strategic shift in how the bank sees its identity within Ghana’s financial sector. Its commercial banking operations may remain broad, but mortgages are once again being placed at the heart of its growth story.
Dr Dzoboku’s target is therefore more than a market-share ambition. It represents an attempt to revive the institution’s original mortgage-focused identity while using modern banking tools, broader products and partnerships to reach more prospective homeowners.
If the bank achieves the 40% to 42% range by year-end, it will reinforce its already substantial presence in Ghana’s mortgage market and underline the importance of housing finance to its next phase of growth.