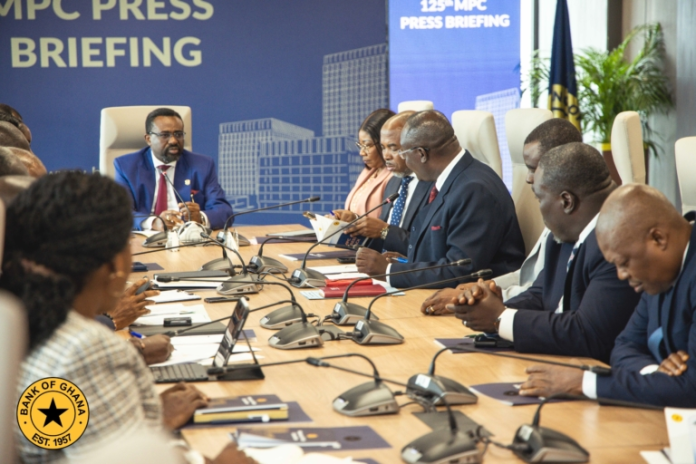
The Bank of Ghana is expected to keep its policy rate at 14% at its September 2026 Monetary Policy Committee meeting, a decision that could leave banks, borrowers and fixed-income investors watching the central bank’s next move closely.
Market research firm IC Insights forecasts the Monetary Policy Committee to maintain the benchmark rate at its current level, despite signs that monetary conditions could support a modest reduction.
The firm’s assessment points to a real policy rate of 9.0%, suggesting that the current monetary stance still provides some room for easing. Yet, with external risks remaining volatile, IC Insights believes the Bank of Ghana may prefer to retain its policy space rather than move quickly toward another rate cut.
That cautious approach could keep borrowing conditions relatively stable across the banking sector over the coming weeks.
Banks Face Another Period of Rate Stability
A decision to maintain the policy rate at 14% would give commercial banks another period of relative certainty in setting lending and deposit rates.
The policy rate serves as an important reference point for monetary conditions, influencing the broader cost of funds in the financial system. While changes in the benchmark do not automatically translate into identical movements in bank lending rates, a prolonged hold generally reduces the immediate pressure for significant repricing.
This means households and businesses could continue to operate under broadly similar credit conditions rather than seeing another sharp shift in borrowing costs.
The situation is particularly important for borrowers who rely on bank financing for working capital, business expansion, asset purchases and other investment activities. A stable policy rate can make financial planning somewhat easier, although actual lending rates remain dependent on individual bank pricing, risk assessments and funding conditions.
BoG Keeps Its Inflation Shield Intact
IC Insights believes the MPC has another reason to stay cautious.
Although the real policy rate provides room for a modest cut, the research firm expects the central bank to preserve its existing policy headroom. This would allow the Bank of Ghana to respond to an unexpected inflation increase without having to reverse course quickly through a rate hike.
The approach reflects the balancing act facing monetary policymakers.
Inflation has moved closer to the lower end of the Bank of Ghana’s medium-term target range, while inflation expectations and core inflation have remained broadly anchored within the target band. However, the central bank has continued to monitor external risks that could put renewed pressure on domestic prices.
At its July 2026 meeting, the MPC maintained the policy rate at 14%, with Governor Dr. Johnson Asiama citing rising external risks to inflation despite continued strength in the domestic economy.
That decision established the 14% rate as the current anchor for monetary conditions, and IC Insights now expects the MPC to extend that position into September.
Treasury Yields Could Become the Next Flashpoint
While the policy rate may remain unchanged, IC Insights is drawing attention to developments in the government securities market.
The research firm believes the 91-day Treasury bill yield has reached a trough and could require upward repricing to restore a positive real yield.
That observation could become significant for banks and fixed-income investors.
Treasury bills remain an important part of Ghana’s financial market, providing banks and other investors with short-term investment opportunities. Changes in Treasury yields can also influence portfolio allocation decisions, liquidity management and the relative attractiveness of different financial instruments.
A rise in the 91-day yield would therefore represent an important market adjustment even if the Bank of Ghana leaves its policy rate untouched.
The prospect of upward repricing also highlights the difference between the central bank’s policy decision and movements across the wider money market. A rate hold does not necessarily mean every market interest rate will remain completely unchanged.
Credit Market Awaits the Next Signal
The September policy decision will therefore be closely watched across Ghana’s banking and financial markets.
Maintaining the 14% benchmark could signal that the MPC wants to consolidate recent monetary developments before considering another adjustment. It would also allow banks to continue operating with a relatively stable benchmark while borrowers avoid an immediate increase in the policy-driven cost of credit.
At the same time, financial institutions will be watching Treasury yields and liquidity conditions for signs of repricing.
The key question is no longer simply whether the policy rate will change. Market participants will also be looking at what the decision means for lending rates, deposit pricing, Treasury bill yields and the broader cost of funds.

14% Hold Keeps Banks and Borrowers Watching
A sustained policy rate of 14% would mean the cost of credit is unlikely to experience a major policy-driven shift over the next two and a half months.
That stability could provide banks and their customers with some breathing room, particularly as businesses assess financing needs and financial institutions manage their loan and investment portfolios.
Yet, the Treasury market may tell a different story if short-term yields begin to move higher.
IC Insights’ expectation therefore places the September MPC meeting at the centre of attention for Ghana’s financial sector. The Bank of Ghana may keep the headline policy rate unchanged, but developments in lending rates and Treasury yields could determine how much the financial system actually feels the impact of the decision.
READ ALSO: Africa Faces Challenge Turning Climate Adaptation Plans Into Investment – FAO