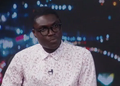
Ghana’s financial sector is facing a fresh legal warning after the Board Chairman of the Securities and Exchange Commission (SEC), Dr Edwin Anani Ennin, raised concerns that depositors could remain dangerously exposed when regulated financial institutions collapse.
Dr Ennin has called for an urgent review of Ghana’s insolvency framework, arguing that the current creditor hierarchy does not adequately recognise the special position of people and businesses that entrust their savings to financial institutions.
His concerns centre on Section 107 of the Corporate Insolvency and Restructuring Act, which determines the order in which creditors are paid when an insolvent institution is liquidated.
Depositors Near the Bottom of the Queue
According to Dr Ennin, the existing legal framework leaves depositors with inadequate protection because they are positioned only above shareholders and certain equity holders in the repayment hierarchy.
“Under the law, it’s like the depositors are only placed above shareholders, preference shareholders and ordinary shareholders,” Dr Ennin said.
“That is how bad I think our law is, that it doesn’t give serious attention to depositors’ funds.”
The warning has reignited debate over whether Ghana’s general corporate insolvency rules are suitable for financial institutions whose operations depend heavily on public confidence.
Unlike conventional investors, depositors typically do not place their money with a bank or other regulated financial institution with the expectation of bearing the commercial risks associated with the institution’s investments and lending activities.
Instead, they expect their funds to be safeguarded and accessible when needed.
‘Trust Money’ at the Centre of the Debate
Dr Ennin described deposits as essentially “trust money”, highlighting the unique relationship between financial institutions and the public.
“If it’s a financial institution, I think that we should make the provision better to cater for the depositors who have given their money to you. Because that was, I call it trust money, and there’s an element of trust.”
Dr Edwin Anani Ennin
That trust is crucial to the financial system.
Banks and other deposit-taking institutions rely on public deposits to provide loans, finance businesses and support economic activity. When people lose confidence in the safety of their deposits, the consequences can extend far beyond an individual institution.
A collapse can trigger panic withdrawals, weaken savings mobilisation and make households and businesses more reluctant to keep funds within the formal financial system.
For a country seeking to deepen financial inclusion and expand access to finance, such a loss of confidence could have serious implications.
Why Financial Institution Failures Are Different
The debate goes beyond determining who gets paid first when an institution collapses.
The failure of an ordinary company can cause significant losses for shareholders, employees, suppliers and creditors. However, the collapse of a bank or deposit-taking institution can have much wider consequences because of its connection to households, businesses and other financial institutions.
A failed financial institution can leave customers unable to access their savings, disrupt business operations and create uncertainty across the financial system.
This makes the treatment of depositors a financial stability issue rather than simply a corporate liquidation matter.
Dr Ennin’s intervention therefore points towards the possibility of a specialised insolvency framework for financial institutions, rather than relying solely on rules designed for ordinary companies.
Stronger Protection Could Change Who Bears Losses
Giving depositors stronger statutory priority would inevitably affect other creditors.
Creditors currently positioned ahead of depositors could face greater exposure if a financial institution becomes insolvent. That could also influence the cost of funding available to financial institutions, as sophisticated creditors reassess the risks associated with lending to banks and other regulated entities.
However, stronger depositor protection could also be justified by differences in financial sophistication.
Large institutional creditors can conduct detailed assessments of an institution’s balance sheet, capital adequacy and risk profile. Ordinary depositors, particularly households and small businesses, generally have limited ability to assess those risks.
Their primary expectation is that placing money with a regulated institution provides a reasonable degree of protection.
Insolvency Reform Could Strengthen Confidence
Any reform would have to work alongside Ghana’s existing deposit protection mechanisms, prudential regulations and financial-sector resolution powers.
Stronger priority for depositors cannot replace effective supervision, adequate capital requirements or early intervention when financial institutions begin experiencing distress.
Instead, a comprehensive framework could ensure that problems are identified early and that failing institutions can be resolved without causing unnecessary disruption.
Such reforms could also provide greater certainty about who ultimately absorbs losses when a financial institution fails.
Ghana’s Financial Sector Has Lessons From Past Failures
The issue carries particular significance for Ghana because the country has previously experienced widespread financial-sector distress.
Failures within the sector can affect thousands of depositors and businesses, with consequences that extend beyond the institutions themselves.
When customers cannot access their funds, businesses may struggle to meet payroll and supplier obligations. Households can lose access to savings, while confidence in financial institutions can deteriorate.
For this reason, the debate over insolvency rules has implications for financial stability, investment, financial inclusion and the broader economy.
A Critical Policy Choice for Ghana
Dr Ennin’s warning ultimately raises a fundamental question about the purpose of insolvency law in the financial sector.
Should the law simply determine how the remaining assets of a failed institution are distributed, or should it also protect public confidence and contribute to financial stability?
His position strongly favours the latter.
Financial institutions may fail in any market economy, and no legal framework can completely eliminate the possibility of distress or liquidation.
However, legislation can determine how losses are distributed when failure occurs.
For Dr Ennin, depositors should not be left looking almost like ordinary unsecured creditors after entrusting their savings to regulated financial institutions.
If deposits are indeed “trust money” and public savings provide the foundation for financial intermediation, then protecting that trust could become a much more explicit objective of Ghana’s insolvency regime.
The warning now places depositor protection firmly on the policy agenda, with potential implications for how Ghana handles financial institution failures and protects public confidence in the financial system.
READ ALSO: GSE Trades GH¢7.3 Million as Index Climbs