Ghana’s transport fare debate has acquired a new macroeconomic dimension as international oil prices return to the upper US$90s, just as operators seek a fare review and inflation has only recently fallen to 5 percent.
Brent crude traded in the mid-to-upper US$90s a barrel on Monday as renewed United States-Iran tensions disrupted tanker traffic around the Strait of Hormuz. For Ghana, the issue is how a sustained energy shock moves through fuel pricing, transport costs, distribution margins and household inflation.
Fuel Costs Are Rewriting the Fare Arithmetic
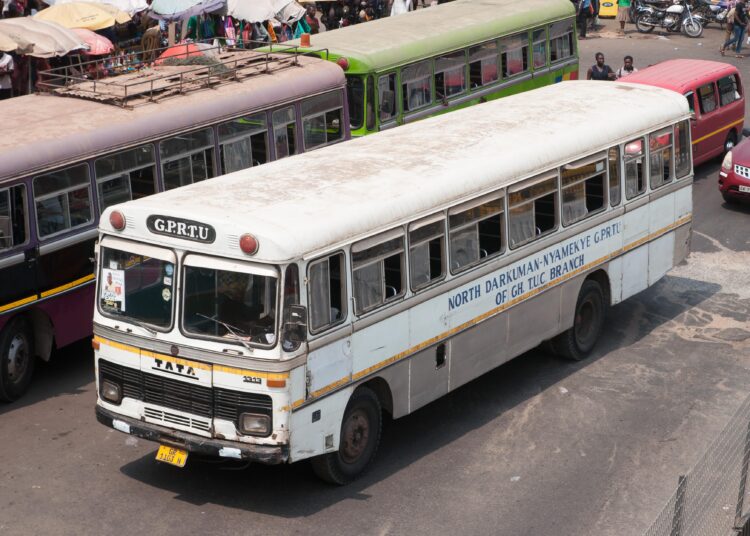
The Ghana Private Road Transport Union (GPRTU) and the Ghana Road Transport Coordinating Council have formally asked the Ministry of Transport to review public transport fares. The Information Services Department confirms that the request is being handled under the Administrative Instrument and consultations are still pending. No new nationwide fare has been approved.
Union officials have publicly floated an adjustment of up to 30 percent, citing fuel and other operating costs. But the ask requires more than applying the oil-price increase directly to fares. The National Petroleum Authority’s pricing framework uses two pricing windows each month and builds ex-pump prices from international product prices, supplier premiums, taxes, levies and margins. Exchange-rate movements and competition among petroleum service providers also affect the final price consumers face.
Brent at US$97 does not mechanically imply a 30 percent increase at the pump or in fares. Any adjustment should reflect weighted changes in fuel, maintenance, insurance, statutory charges and vehicle financing, rather than assuming every cost component moved equally. The relevant pass-through also depends on how far higher fuel costs compress operator margins before a review, whether vehicles run near capacity, and how much pressure can be absorbed through route efficiency. Those differences matter because one uniform percentage can affect short urban trips and long-distance services very differently.
A 30% Adjustment Needs Cost-Based Evidence
The dispute is therefore partly about measurement. Fuel is a major variable cost for taxis, trotros and intercity operators, so persistent increases can squeeze margins. But fuel’s share of total cost differs by vehicle type, route length, traffic conditions and load factor.
The same logic applies to spare parts and maintenance. If some inputs have remained broadly stable while fuel has risen, using a uniform 30 percent adjustment risks overstating the increase required to restore operator margins. Conversely, if insurance, tyres, lubricants or statutory charges have risen materially, excluding them would understate the pressure on operators.
Fare setting is therefore stronger when the weights assigned to each input are transparent. That protects drivers from losses while shielding households from unjustified increases.
Transport Costs Can Spread Beyond the Passenger
The fare debate extends beyond commuters. Road transport is an intermediate input across the economy. Traders move food to urban markets, firms distribute goods and workers commute. When transport costs rise, businesses absorb part through lower margins or pass it into final prices.
That transmission is especially important now because the Ghana Statistical Service reports headline inflation of 5.0 percent in August, up from 4.6 percent in July. Food inflation was 3.0 percent, while non-food inflation stood at 6.8 percent. A transport shock does not automatically produce a new inflation surge, but repeated fare and freight increases can broaden price pressures by raising the cost of distribution and changing household inflation expectations.
Government has already recognised this channel. In August, a one-month GH¢2 per litre reduction in the regulatory margin on diesel was explicitly intended to cushion consumers, prevent transport fare hikes and contain inflationary pass-through. The intervention illustrates the policy trade-off: cushioning fuel costs can slow immediate transmission, but it does not remove the underlying external shock if international prices remain elevated.
September MPC Faces a Fresh Supply-Side Risk
The Bank of Ghana now faces the same distinction. Its policy rate remains at 14 percent while inflation is below the 6 to 10 percent target band. The Bank’s July deliberations nevertheless highlighted petroleum prices, utility tariffs, food supply and inflation expectations as upside risks, showing why current inflation alone cannot determine the next rate decision.
The 132nd Monetary Policy Committee meetings are scheduled for September 23 and 24. By then, the Committee will have to judge whether higher oil and transport costs represent a temporary relative-price adjustment or the beginning of broader second-round inflation through fares, freight charges and expectations.
For households, the priority is affordability. For drivers, it is commercial viability. For monetary policy, the concern is whether an external oil shock becomes embedded in domestic pricing behaviour. Ghana’s fare negotiations should therefore be treated as more than a transport-sector dispute. They are an early test of whether the country’s recent disinflation can withstand a fresh supply-side shock without forcing households, firms and the central bank into another costly adjustment.
READ MORE: Ghana’s 5% Inflation Reopens Debate Over BoG’s 14% Policy Rate